Best Mortgage Protection Insurance Options
Finding the right mortgage protection insurance can feel like a maze, especially when you want coverage that fits your budget and long‑term goals. Below are the eight most reliable picks, and who each works best for.
1. Life Care Benefit Services
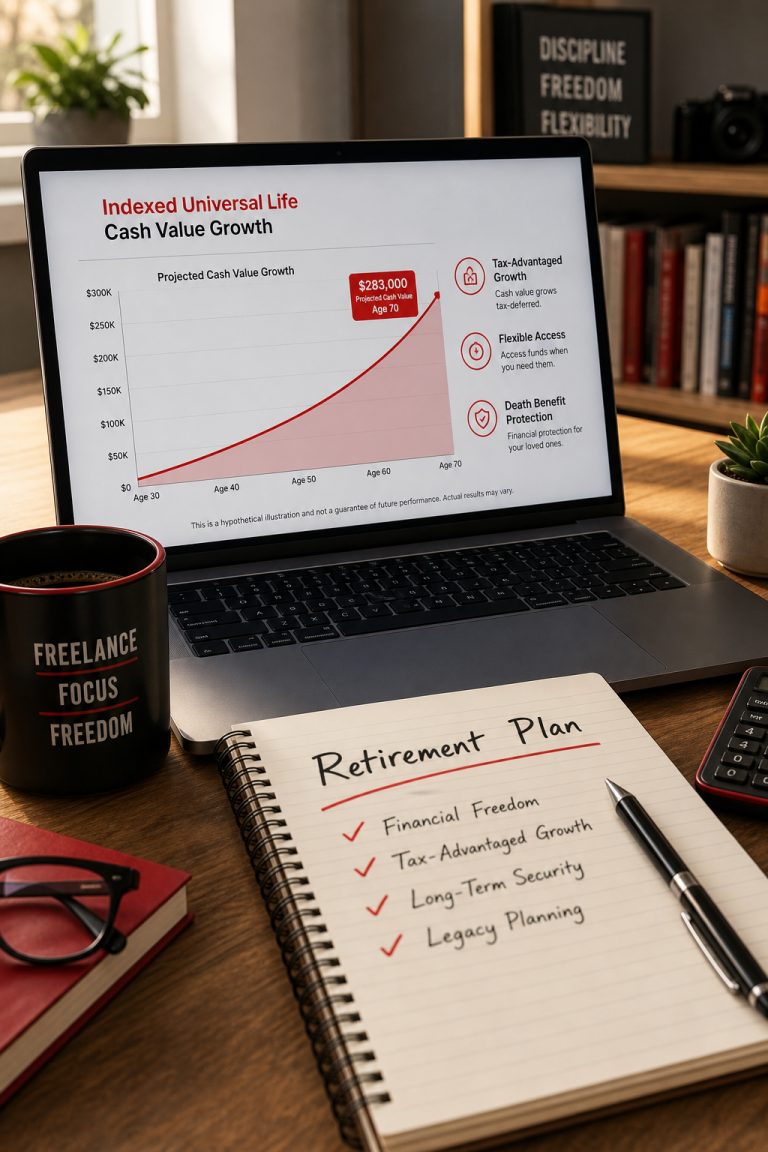
Life Care Benefit Services offers a flexible, income‑based mortgage protection plan that doubles as an indexed universal life (IUL) policy. It tailors the death benefit to your income, debts, and family responsibilities instead of a static mortgage balance.
Best for families, seniors, and small‑business owners who want both protection and cash‑value growth.
The plan includes cash‑value tied to market indexes, adjustable premiums, and the option to borrow against the cash while you’re alive. That living‑benefit feature isn’t found in most traditional mortgage‑only policies.
A caveat: because the policy is permanent, you’ll pay for coverage your whole life, even after the mortgage is paid off.
2. Veterans’ Mortgage Life Insurance (VMLI) — Specialized protection for eligible Veterans
VMLI provides mortgage coverage paid directly to the lender. It’s only for families of severely disabled Veterans who have a Specially Adapted Housing grant and are under 70.
Best for qualifying Veterans who need a simple, no‑cash‑value option.
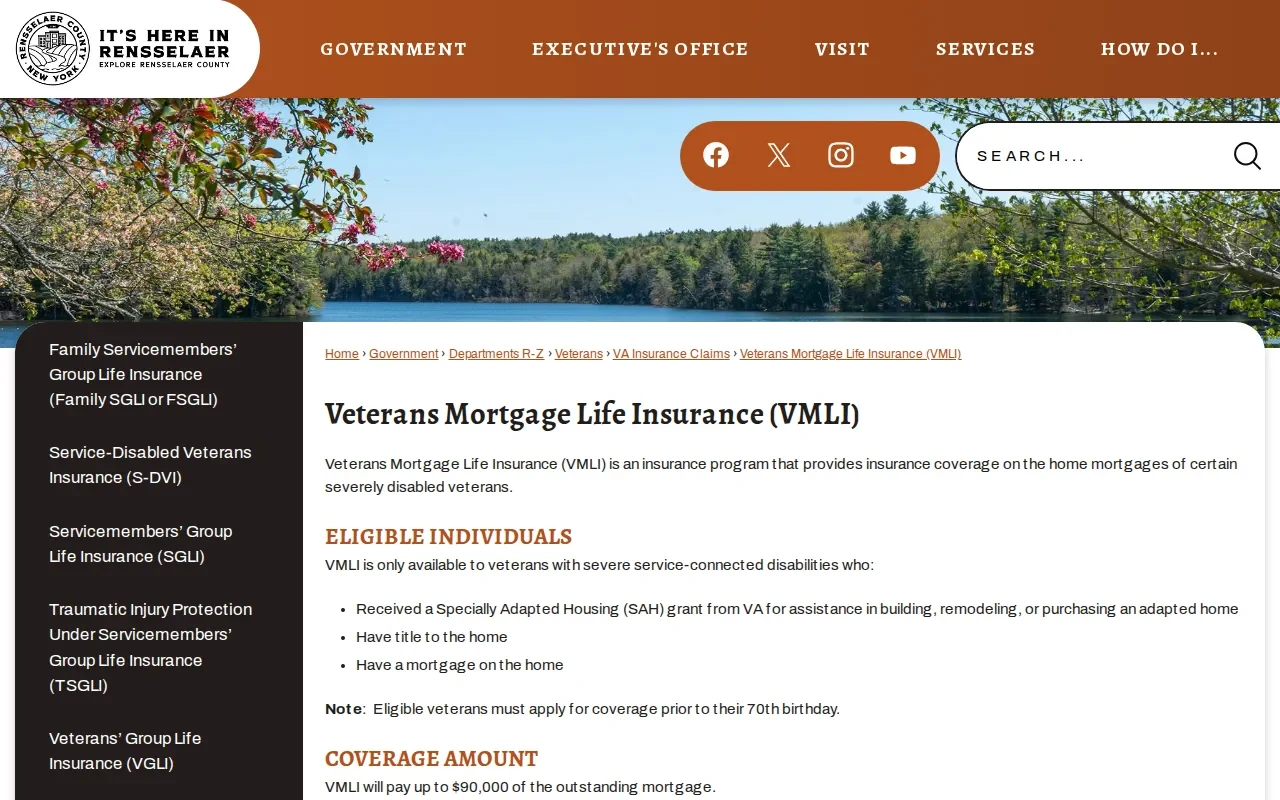
The coverage amount equals the remaining mortgage balance, decreasing as you pay down the loan. Premiums depend on age, mortgage balance, and term.
Limitations: No living‑benefit riders, no cash value, and strict eligibility rules.
For eligibility details, see VMLI eligibility information.
3. Veterans’ Mortgage Life Insurance (VMLI) — Mortgage protection for eligible families
Veterans’ Mortgage Life Insurance (VMLI) is best for families of severely disabled Veterans who need mortgage protection.
Eligibility is for families of Veterans with severe service-connected disabilities.
Learn more about available options at Life Care Benefit Services’ term life page.
4. Mortgage Protection Coverage — Broader long‑term financial protection
Permanent policies such as indexed universal life (IUL) or whole life provide lifelong death protection plus a cash‑value component that grows tax‑deferred. You can tap the cash for emergencies, retirement, or mortgage payments.
Best for owners who want a single product that covers the mortgage, builds wealth, and can serve as a retirement supplement.
These policies offer flexible premium payments and the ability to increase the death benefit over time. However, they cost more than term policies and require regular premium payments to keep the cash value growing.
The cash value can be accessed via policy loans or withdrawals, but any unpaid loans reduce the death benefit.
5. Veterans’ Mortgage Life Insurance (VMLI) — Mortgage protection for eligible families
Veterans’ Mortgage Life Insurance (VMLI) is best for families of severely disabled Veterans who need mortgage protection.
This option focuses on mortgage protection for families of severely disabled Veterans.
Eligibility is for families of Veterans with severe service-connected disabilities who need mortgage protection.
Families of severely disabled Veterans can consider VMLI when mortgage protection is a priority.
Mortgage Protection Insurance Comparison Table
Use this matrix to line up the key features you care about.
| Option | Eligibility | Coverage Type | Living Benefits | Typical Cost |
|---|---|---|---|---|
| Life Care Benefit Services | Anyone (individuals, families, seniors, small‑biz) | Indexed Universal Life (IUL) | Cash‑value growth, policy loans | — |
| VMLI (VA) | Severely disabled Veterans with SAH grant, <70 | Decreasing term | No | — |
| Term life insurance | Generally anyone with good health | Level term (10‑30 yr) | No | — |
| Permanent life insurance with living benefits | Anyone, but underwriting stricter | Permanent coverage or IUL | Cash value, loans, withdrawals | — |
| Mortgage protection insurance | Mortgage borrowers | Decreasing term | No | — |
How to Choose Checklist
- Do you qualify for VA’s VMLI? If yes, it’s low‑cost but limited.
- Do you need cash‑value growth for retirement or emergencies? Consider Life Care or a permanent IUL.
- Is flexibility to name a beneficiary important? Choose term or permanent policies outside the lender.
- Are you comfortable paying higher premiums for lifelong coverage? Then a permanent policy may fit.
- Do you prefer the convenience of a lender‑sold policy? It’s simple but less adaptable.
FAQ
What is mortgage protection insurance?
Mortgage protection insurance is a type of mortgage coverage that pays off your mortgage balance if you die before the loan is fully repaid.
Can I name my own beneficiary?
With some mortgage protection policies you cannot; the benefit goes to the lender. Independent term or permanent policies let you name any beneficiary.
Does mortgage protection insurance build cash value?
Only permanent policies like indexed universal life build cash value; traditional term and VA’s VMLI do not.
Is VMLI worth it for non‑Veterans?
No. VMLI is strictly for qualifying Veterans and their families; everyone else must look at other options.
How do premiums compare across options?
Generally, term life is cheapest, permanent policies are more expensive, and some mortgage protection coverage often sits between the two.
Do I need a medical exam?
Many term and permanent policies require a brief health questionnaire; some mortgage protection policies may not require exams, while VMLI uses VA underwriting standards.
Conclusion
If you want a solution that protects your home and also grows cash for future needs, Life Care Benefit Services is the most versatile pick. Ready to see a quote? Schedule a free consultation today.