Best Indexed Universal Life for College Tuition Planning (2026)
College costs keep rising, and the 529 plan can feel like a straight‑jacket. Indexed universal life (IUL) policies let you grow cash value tax‑free while keeping a death benefit. Here’s a short list of the best IUL options for tuition funding and who each one fits.
1. Life Care Benefit Services
Life Care Benefit Services offers an IUL that blends protection with flexible cash‑value growth. It’s built for families who want a single policy to cover both life insurance and college savings.
Life Care Benefit Services works with over 50 top‑rated carriers, so you can pick a carrier that matches your budget and credit rating.
Why it earns a spot:
- Personalized quotes let you see how contributions affect cash value over time.
- Living‑benefit riders add chronic‑illness protection without extra paperwork.
- Policy loans are tax‑free if the policy stays non‑MEC, letting you pull funds for tuition without penalties.
The downside is that the floor rate and participation details aren’t public, so you’ll need to ask for a full illustration before you commit.
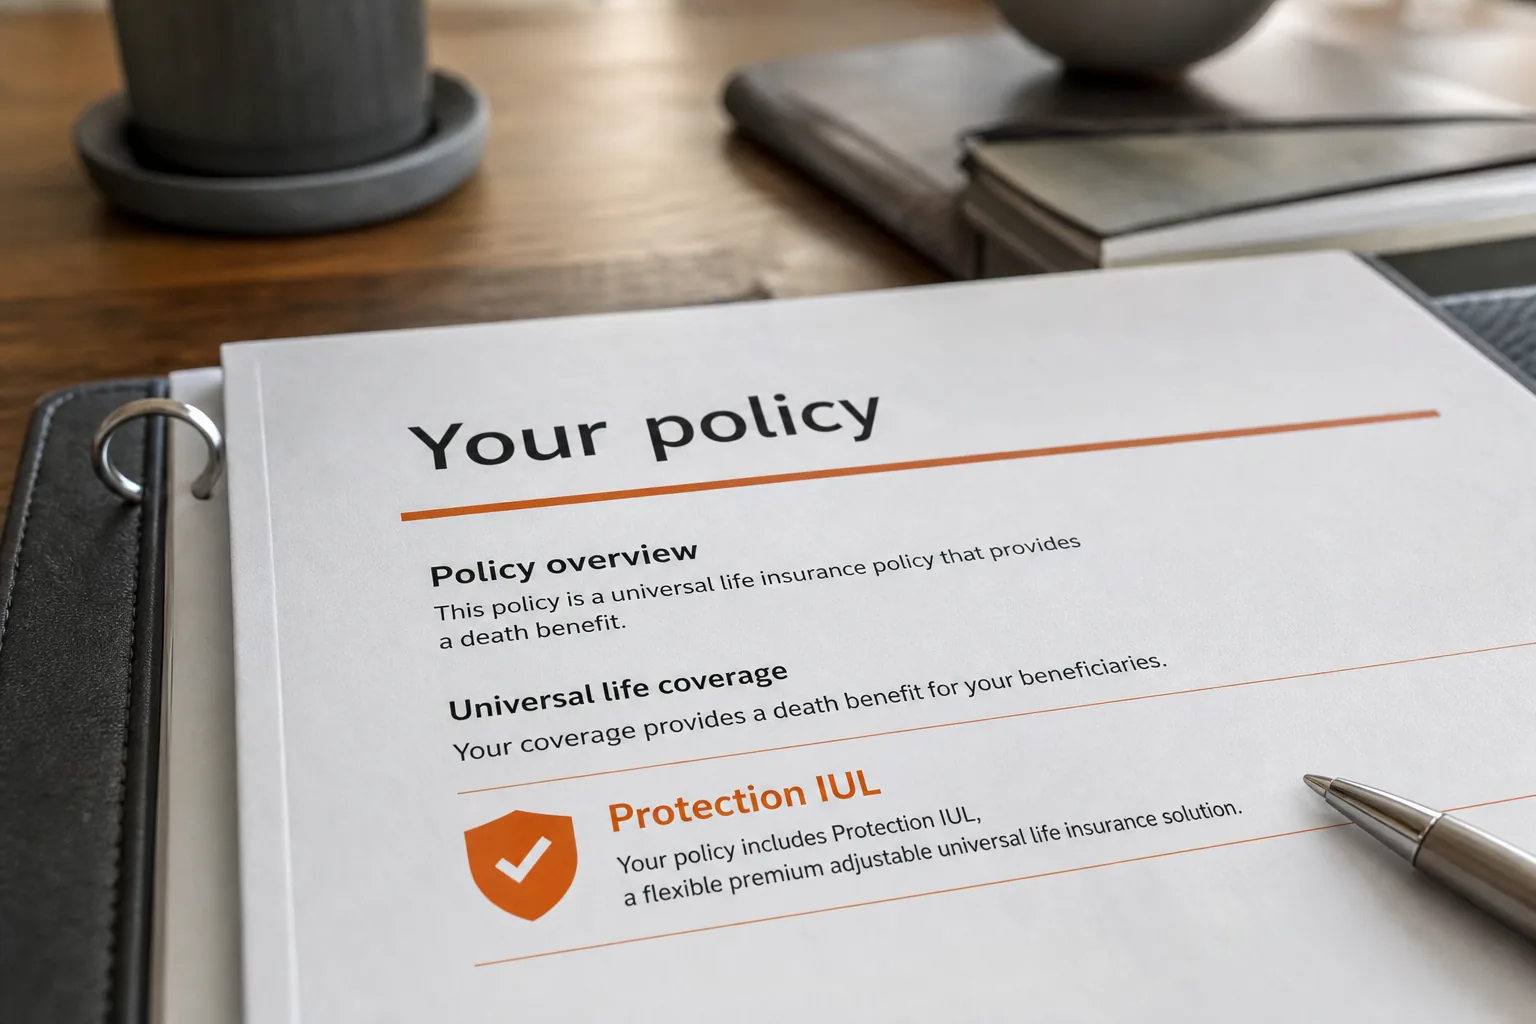
2. Prudential Protection IUL — A policy option for future needs and unexpected expenses
Prudential’s Protection IUL focuses on a solid death benefit while still offering cash‑value growth.
The product is meant for families who want a safety net for health‑related costs or unexpected events, not just tuition.
Key reasons to consider it:
- It offers a 0% floor, meaning you won’t lose cash value when the index drops.
- Multiple indexed crediting options let you choose a fixed rate or an index‑linked rate.
- Policy loans are available once the cash value builds, and they stay tax‑free under IRC 7702.
One caution: the floor is 0%, which defeats the “downside protection” many parents expect from an IUL. Make sure you understand the cap rates before locking in.
3. Participating‑index IUL policies — Greater upside potential with capped returns
A participating-index IUL can offer participation in index gains, but it may cap credited interest.
What makes it stand out:
- Some policies may allow you to lock in a positive index value, helping protect gains from later market drops.
- Some policies may automatically lock the index when it reaches a target you set.
- The policy’s death benefit stays tax‑free, and cash value grows tax‑deferred.
The trade‑off is a cap on the credited rate, so you won’t capture the full market upside in high‑growth years.
4. Protection-focused IUL policies — Support for unexpected expenses and future health-related needs
These policies can help cover unexpected expenses and future health-related needs.
They may be worth considering when your planning priorities include protection alongside long-term financial goals.
Benefits include:
- Support for unexpected expenses.
- Planning for future health-related needs.
- A 0% floor rate.
Review the policy details and your college tuition goals with Life Care Benefit Services before choosing coverage.
5. Flexible IUL coverage — Planning for unexpected expenses and future health-related needs
This approach may help families plan for unexpected expenses and future health-related needs.
Review the policy design and funding approach carefully to determine whether it fits your college planning goals.
Pros:
- Can help address unexpected expenses.
- Can support planning for future health-related needs.
- Allows coverage decisions to be evaluated alongside broader financial goals.
Cons:
- Policy details require careful review.
- Suitability depends on each family’s needs and financial circumstances.
Speak with a qualified professional before using life insurance as part of a tuition-planning strategy.
6. Protection-focused indexed universal life policy — Support for future needs
A protection-focused indexed universal life policy can help cover unexpected expenses and future health-related needs.
Its 0% floor rate can help provide a baseline for indexed interest crediting, while policy details and suitability vary.
Key points:
- Designed to address unexpected expenses.
- Can support future health-related needs.
- Includes a 0% floor rate.
Review the policy terms carefully with a qualified professional before choosing coverage for college tuition planning.
7. Estate-planning coordination for suitable families
Estate-planning coordination may help suitable families align life-insurance decisions with broader financial goals.
This type of planning can involve professional guidance, careful documentation, and coordination with other advisers.
Considerations:
- Review how ownership and beneficiary choices fit the overall estate plan.
- Understand ongoing administrative responsibilities before selecting a structure.
- Coordinate decisions with qualified legal and tax professionals.
Planning may involve more complex paperwork, ongoing administration, and limited flexibility after implementation.
For additional estate-planning background, review this resource.
8. Family-owned IUL structures — Ownership and control considerations
Family-owned IUL structures can be considered when evaluating life insurance with living benefits and long-term planning goals.
Review ownership, beneficiaries, premiums, and policy terms with a qualified professional.
Considerations:
- Ownership and beneficiary choices should align with the family’s goals.
- Premium responsibilities and policy terms should be reviewed before applying.
Important:
- Changes in ownership require careful review.
- Request a consultation to discuss whether an IUL fits your planning needs.
9. Coordinating business protection and retirement goals
Entrepreneurs often layer basic life coverage for payroll protection with an IUL for cash‑value growth.
This hybrid lets the business keep affordable death coverage while the IUL builds wealth for a child’s tuition.
Highlights:
- The coverage side is affordable and covers business loans.
- The IUL side grows tax‑deferred and can be accessed for college costs.
- Both policies can be owned by the business, pulling cash‑value into a retirement plan later.
Make sure the total premiums don’t exceed the cash‑flow capacity of the business, or the strategy can backfire.
10. Term‑plus‑invest hybrid approach — Lower‑cost protection with separate college savings
Pairing lower-cost temporary coverage with a separate savings vehicle gives families the protection of temporary insurance and the flexibility of saving independently.
This isn’t an IUL, but many families choose it when they want a clear separation between insurance and investing.
| Feature | Term + Invest | IUL |
|---|---|---|
| Death benefit cost | Low (pure term) | Higher (permanent) |
| Cash‑value growth | Depends on market choice | Tax‑deferred, indexed with floor |
| FAFSA impact | Term assets not reported; investment reported | Cash value generally not reported (depends on ownership) |
| Liquidity | Full access to investment account | Policy loans, but may affect death benefit |
How to Choose the Right IUL for Tuition
- Check the floor rate, a 0% floor means no downside protection.
- Ask for the participation and cap rates; they drive upside potential.
- Make sure the policy stays non‑MEC so loans stay tax‑free.
- Consider ownership, parent, grandparent, or trust, based on FAFSA impact.
- Model cash‑value growth with a conservative cap (5‑6%) to avoid over‑optimism.
FAQ
Can I use an IUL instead of a 529 plan?
Yes, you can fund college with an IUL, but the cash value grows tax‑deferred and loans are tax‑free only if the policy remains non‑MEC. Unlike a 529, you aren’t limited to qualified education expenses.
How does an IUL affect FAFSA?
Generally, the cash value of a parent‑owned IUL isn’t counted as a reportable asset on FAFSA, which can keep the Expected Family Contribution lower than a comparable 529 balance.
What is the floor rate and why does it matter?
The floor rate is the minimum interest credit the policy guarantees each year; a 0% floor means the policy won’t lose value in a down market, but it also offers no positive guarantee.
Are policy loans taxable?
Policy loans are not taxable as long as the policy stays in force and is not a Modified Endowment Contract (MEC). If the loan isn’t repaid and the policy lapses, the outstanding amount becomes taxable.
What happens if I stop funding the IUL early?
Early surrender can trigger surrender charges that erode cash value. Some policies have a catch‑up provision that lets you over‑fund later, but you’ll still pay fees on the reduced cash value.
Conclusion
If you want a single solution that blends protection with tuition funding, start with Life Care Benefit Services. Request a personalized illustration today and see how the cash value can grow for your child’s education.