Whole Term Life Insurance vs Term Policy: Cost, Coverage & Fit
Choosing between whole term life insurance and a term policy feels like a big decision. One gives you lifelong protection and cash value; the other offers cheap, temporary coverage. Below we break down the key differences so you can see which one fits your life.
We analyzed 74 comments and questions from Reddit, YouTube and Quora about whole life versus term life insurance and found that 30% mentioned cash value and return calculations.
Cost and Premiums: Lifetime Payments vs. a Set-Term Rate
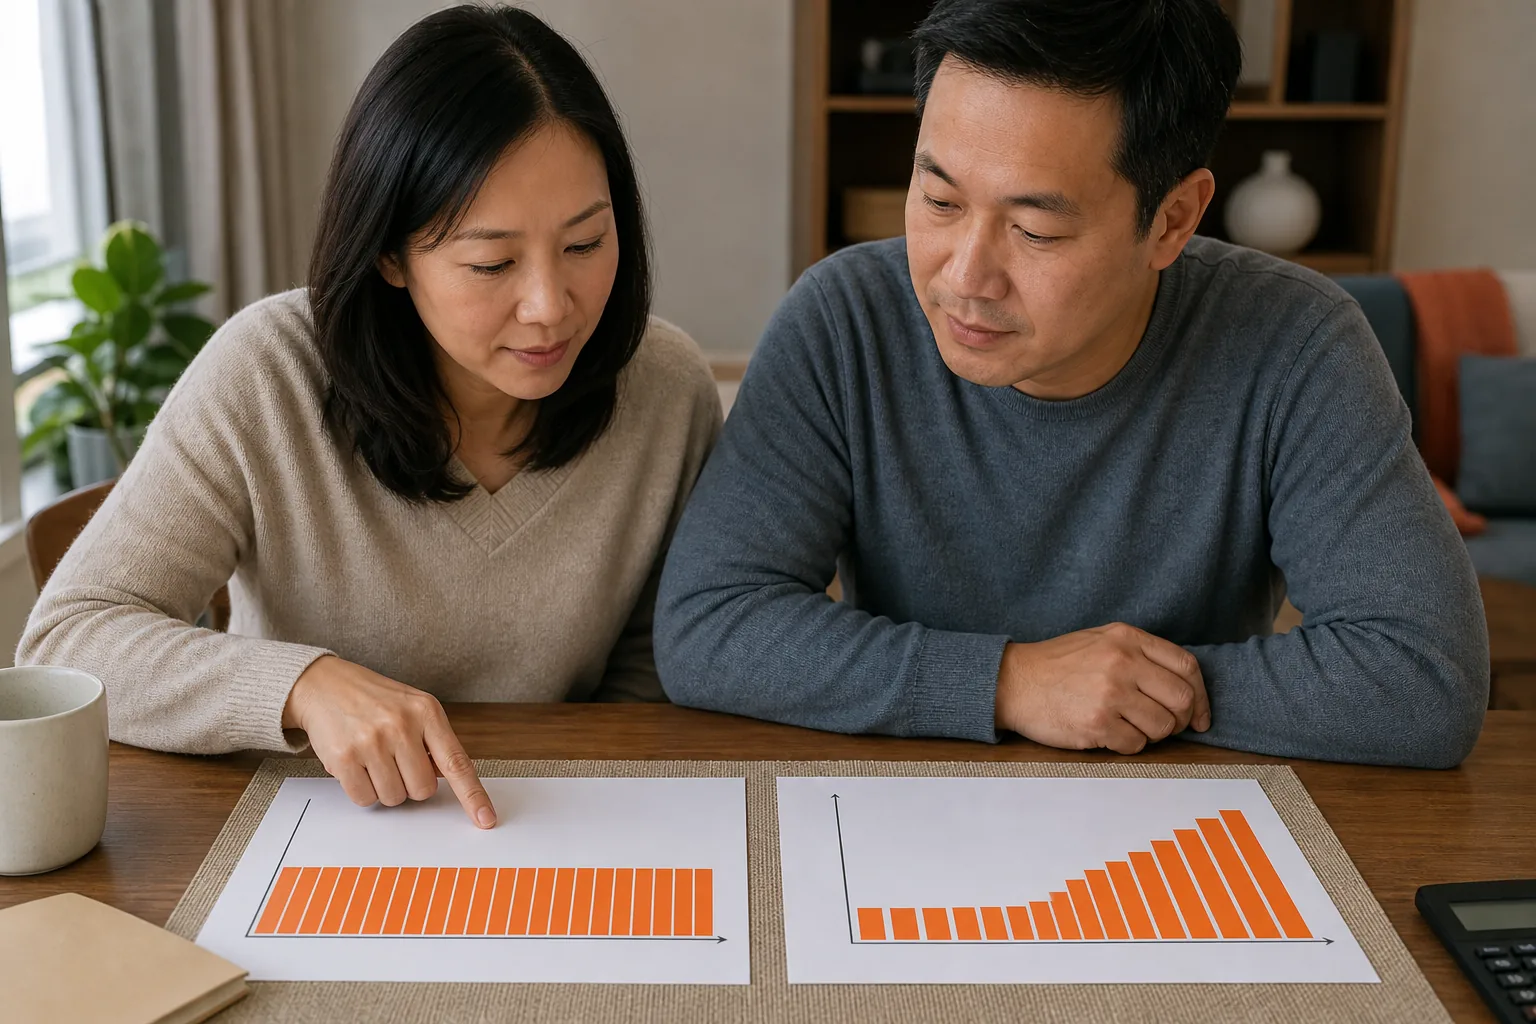
Whole life premiums stay level for the whole time you own the policy. You pay more each month, but the amount never changes. Term policies charge a lower, fixed amount for the length of the term, then the price jumps if you renew after the period ends.
Allstate notes that term insurance “tends to be less expensive than whole life insurance” and that the level premium can disappear once the term ends, forcing you to either renew at a higher rate or let the coverage lapse. Allstate explains the cost gap and why the cheaper upfront price of term can turn into higher costs later.
Because whole life builds cash value, part of each premium goes into a savings‑type component. That means the higher price buys you a living benefit you can tap later, while term leaves every dollar as pure death‑benefit cost.
For families on a tight budget, the lower term premium often feels like the only realistic choice. For high‑net‑worth households, the permanent premium can be justified by the tax‑advantaged cash value and estate‑planning advantages.
Cash Value: What Whole Life Builds That Term Coverage Does Not
Whole life insurance provides lifelong protection and accumulates cash value that grows tax-deferred. The cash value can be borrowed against. These features can make whole life a fit for people seeking both lifetime coverage and cash value accumulation.
Whole life cash value can be borrowed against. Read more about cash value and policy features.
Term policies have no cash‑value component. They provide coverage for a selected term, commonly 10 to 30 years, and end when that term expires.
Term life insurance typically has level fixed annual premiums throughout the term, while whole life is designed to provide protection for an entire lifetime. Consider which coverage length and features fit your needs when comparing whole life insurance and term policies.
Whole life accumulates cash value over time, while term life does not build cash value. Comparing these features can help you decide whether you want lifelong protection with cash value or coverage for a set term.
Coverage Length and Flexibility: Lifetime Protection vs. a Chosen Term
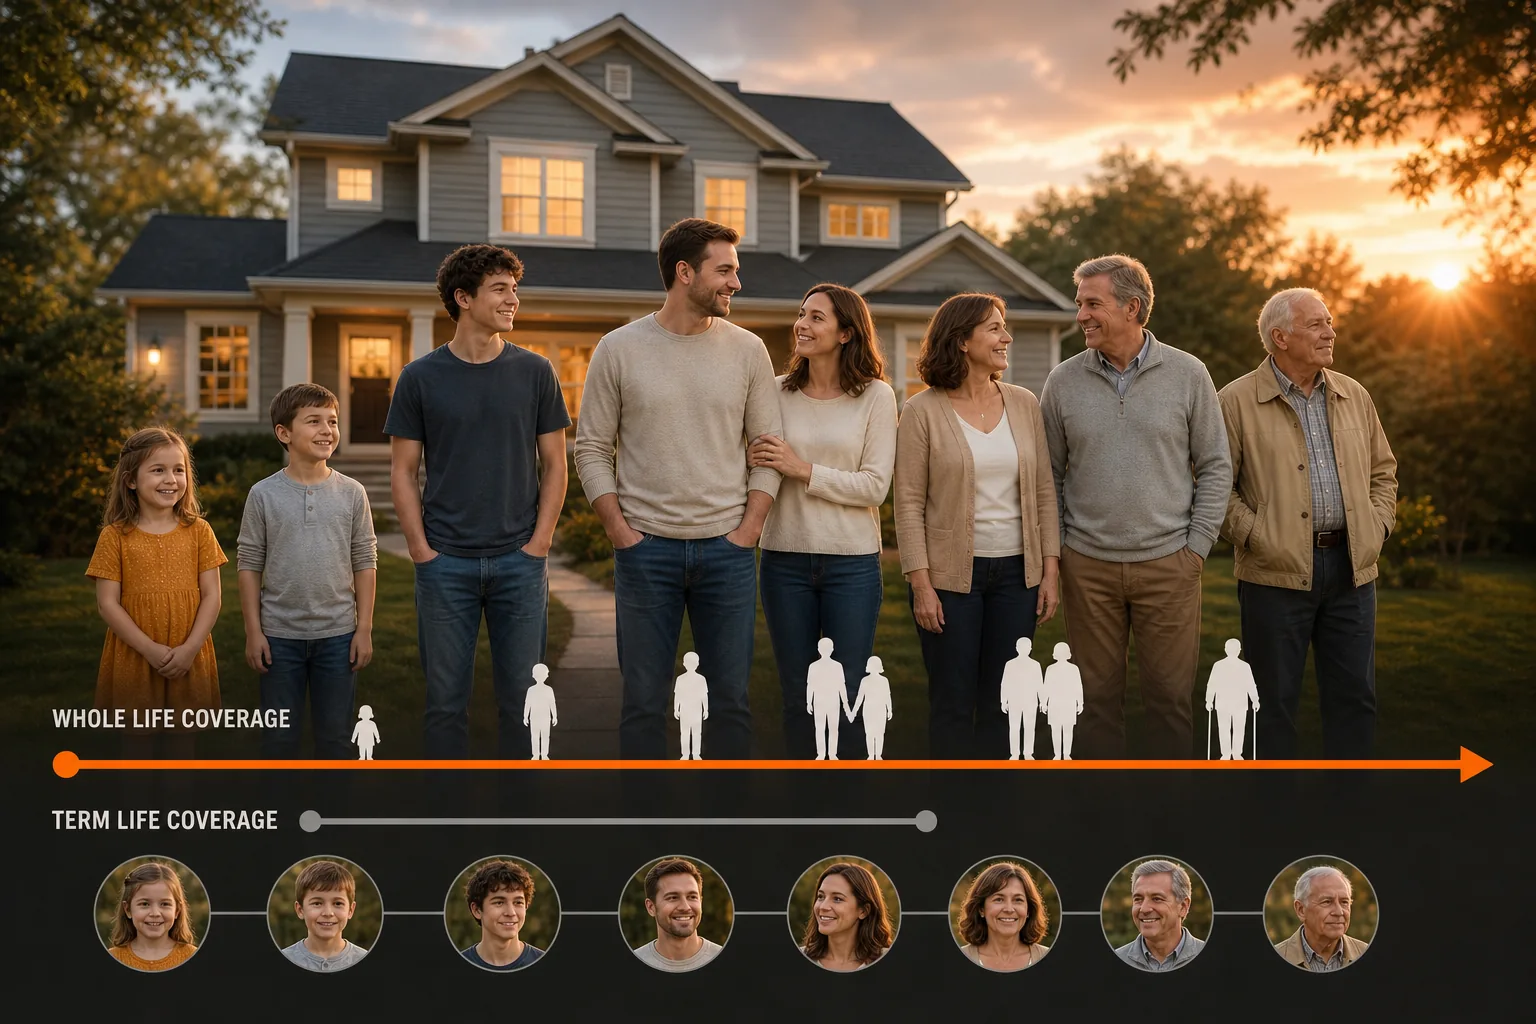
Whole life guarantees coverage for your entire life, as long as you keep paying premiums. There’s no expiration date, no need to re‑qualify, and the death benefit is always there.
Term insurance covers you for a set number of years, most commonly 10, 20 or 30. When the term ends, the coverage stops. If you still need protection, you must either renew (at a higher price) or buy a new policy.
Progressive explains that “term life is affordable and offers coverage for a set period of time” while whole life “has higher premiums but offers lifelong coverage.” Progressive’s guide outlines the trade‑offs.
Because whole life never expires, it’s the go‑to choice for estate planning, long‑term care funding, or leaving a legacy. Term works best for temporary needs like paying off a mortgage, covering kids’ college years, or bridging a career gap.
Below is a quick side‑by‑side view of the two options.
| Feature | Whole Life | Term Policy |
|---|---|---|
| Duration | Lifetime (as long as premiums are paid) | Fixed term – 10, 20, or 30 years |
| Renewability | Not applicable – policy never ends | Often renewable, but at higher rates |
| Conversion option | Not needed, already permanent coverage | Many policies let you convert to permanent coverage |
| Typical use cases | Estate tax planning, lifelong protection, cash‑value savings | Mortgage protection, income replacement for a set period |
Which Is Better for You? Family Needs, Mortgage Protection, and Long‑Term Plans
If you’re a young family with a mortgage, a term policy often makes sense. It gives you enough coverage to pay off the house if something happens, and the low premium leaves money for other goals.
For families with special‑needs dependents, or owners who want a tax‑free legacy, whole life shines. The cash value can fund long‑term care, and the guaranteed death benefit protects heirs no matter when you die.
High‑net‑worth individuals often use whole life as part of an estate‑tax strategy. The policy’s cash value can be placed in an irrevocable life‑insurance trust, shielding it from creditors and providing liquidity for estate taxes.
Many people start with affordable term coverage and later add a whole‑life policy for the years when they need permanent protection. A conversion rider on a term policy can make that switch smoother.
Life Care Benefit Services offers permanent life‑insurance options that include cash‑value growth and estate‑planning features. Their advisors can match you with a policy that fits both your budget today and your legacy goals for tomorrow. Read how Life Care Benefit Services helps families choose.
Verdict
Term life wins for low‑cost, short‑term needs like a mortgage or college funding. Whole life wins when you need lifelong protection, cash‑value savings, or estate‑planning power. If your budget allows and you value the cash‑value benefit, whole life is the better fit. If you only need coverage for a defined period, term gives you the most bang for your buck.
Frequently Asked Questions
What is the main difference between whole life and term life?
The main difference is that whole life provides permanent coverage and builds cash value, while term life offers temporary coverage with no cash‑value component.
Can I convert a term policy to whole life later?
Many term policies include a conversion rider that lets you switch to a permanent policy without a new medical exam, usually within a set window.
How does cash value affect my death benefit?
Any loans or withdrawals you take from the cash value reduce the death benefit, because the insurer pays out the remaining amount.
Are whole‑life premiums really level for life?
Yes, as long as you keep the policy in force, the premium stays the same; you won’t face age‑based increases.
Is term life ever more expensive than whole life?
Term is cheaper up front, but if you renew after the term ends the new premium can be much higher than a comparable whole‑life premium.
Do I need an agent to buy either policy?
Working with a licensed insurance advisor helps you compare quotes, understand riders, and choose the policy that matches your financial goals.
Conclusion
If you need cheap, short‑term protection, term life is our recommendation. If you want lifelong coverage, cash‑value growth, and estate‑planning benefits, go with whole life. Talk to a Life Care Benefit Services advisor today to get a personalized quote and see which option fits your family’s future.