IUL Estate Planning Benefits: Steps for Families
Could an indexed universal life policy help protect your family and pass money to your heirs? The IUL estate planning benefits can include permanent coverage and an income-tax-free death benefit, but they depend on how the policy is funded and owned. Use these steps to check whether an IUL fits your family’s plan, and what to review before you buy or change a policy.
We analyzed 66 comments and questions from Reddit, YouTube and Quora about IUL estate planning benefits and found that 21% mentioned a tax-free death benefit.
Step 1: Define Your Estate Planning Goals and Coverage Needs
Start with the job you want the policy to do. An IUL is permanent life insurance with a death benefit and a cash value account. The cash value may earn interest based on a market index, subject to the contract’s crediting rules. You don’t own shares in that index.
For estate planning, the main question is what your family may need when you die. The death benefit could provide money for a surviving spouse, help balance an inheritance, or give heirs funds without selling a home or business right away. These are goals to test against the policy’s cost and terms, not guaranteed results.
Estimate the amount your family might need. Include debts you want paid, income support for dependents, and any funds meant for a child or other heir. Then compare that need with your current coverage and other assets. An IUL may be one part of a plan, but it shouldn’t replace cash reserves or other coverage without a clear reason.
Next, decide whether you also want access to cash while you’re alive. Cash value may be available through a loan or withdrawal, but using it can lower the amount left to beneficiaries. If your main goal is a set death benefit, ask whether the policy design supports that goal even when cash value growth is lower than shown in an illustration.
Universal life policies can offer flexible premium payments and include a cash account alongside the death benefit. That flexibility can help when income changes, but it also means the policy needs active attention.
Write down your coverage goal and your acceptable premium range before reviewing policy illustrations. That gives your advisor a clear brief instead of a vague request for “more growth.” Life Care Benefit Services can help families discuss coverage needs, budget, and the trade-offs among available options.
Step 2: Understand IUL Death Benefits and Tax Treatment
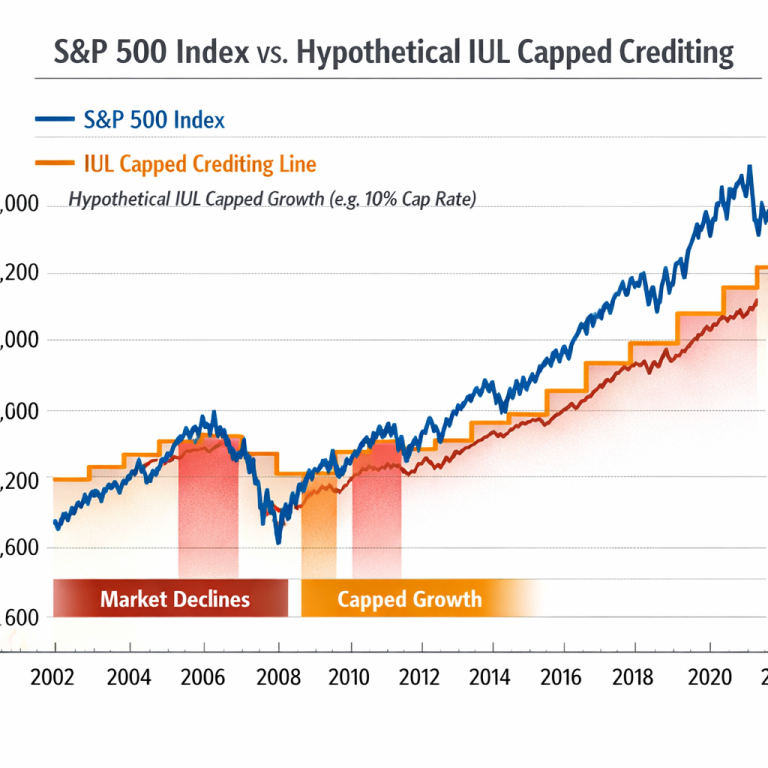
In an IUL, part of the premium pays policy costs. The rest may build cash value. The insurer credits interest using an index-based method set by the contract. A cap can limit the credited gain. A floor sets a minimum crediting rate for the index formula, but it doesn’t mean every policy cost disappears or that cash value can’t fall after charges.
That distinction matters. An IUL isn’t a direct investment in the index. The policy’s results depend on its crediting terms, charges, premium timing, and how long it stays in force. Ask for the current cap, floor, and participation rate, which determines how much of an index change enters the crediting formula. Then ask how those terms could change under the contract.
Cash value growth is generally tax-deferred while it remains in the policy. That is different from saying every way of taking money out is tax-free. Loans and withdrawals follow tax rules and contract terms. A loan accrues interest and can reduce the death benefit. If policy debt grows or the policy lapses, the effect may be serious, so ask a tax professional to review your specific plan.
The death benefit is generally paid to beneficiaries free of federal income tax. With named beneficiaries, the proceeds generally pass to heirs outside probate.
Income tax and estate tax are different questions. A benefit may be free of income tax yet still count as part of the insured person’s taxable estate, depending on ownership and control. Don’t assume an IUL automatically avoids estate tax. Ask an estate attorney and tax professional to review the policy alongside your other assets.
When you compare illustrations, look at more than the projected cash value. Check the guaranteed values, the assumptions behind the non-guaranteed values, and the projected death benefit. The illustrated result is not a promise.
Step 3: Coordinate Policy Ownership, Beneficiaries, and Trusts
Before changing a beneficiary or owner, map who holds each role. The policy owner controls the contract. The insured person is whose life the policy covers. The beneficiary receives the death benefit. One person can hold more than one role, but each choice can affect control and estate planning.
If you name a person directly, the insurer generally pays that person under the beneficiary designation. If you name a trust as beneficiary, the trustee receives and manages the proceeds under the trust terms. That may help when a beneficiary is a minor or when you want distributions made over time instead of as one large payment.
A revocable living trust can help coordinate how assets are managed if you become unable to handle them. But if you retain control over the trust and policy, the death benefit may still be part of your taxable estate. A trust as beneficiary is also not the same as a trust owning the policy. Decide which outcome you need before changing paperwork.
An irrevocable life insurance trust, often called an ILIT, may be used in estate tax planning. The insured person generally gives up control of a policy owned by an ILIT. That trade-off is significant: the trustee must follow the trust terms and handle policy duties, including premium payments. It isn’t a simple form change.
For a new policy, have your estate attorney and insurance professional coordinate before the application is completed. For an existing policy, get legal and tax advice before transferring ownership. A transfer can raise legal or tax issues, and the right approach depends on the policy and your family’s plan.
Check the beneficiary form after major life changes, such as a marriage, divorce, or the birth of a child. A trust document and a policy designation can point in different directions. Keep them aligned, and make sure the trustee knows where to find the policy details.
Step 4: Set Premiums and Evaluate Cash Value Realistically
Flexible premiums can make an IUL seem easy to fit around changing income. But flexibility doesn’t mean the policy can thrive on any payment schedule. Insurance costs and other charges continue. If you pay less than the policy needs over time, cash value may decline and the policy may need more funding to stay active.
Set a premium plan you can keep in an ordinary year, not only when income is high. Then ask what happens if you pay less for a period. Request an illustration that shows how the policy may perform under different assumptions, including lower credited interest. Check whether it still supports your coverage goal.
Understand the index terms before you focus on a growth projection. The cap limits the amount credited under a particular formula. The participation rate sets the share of index change used in that calculation. The floor sets a minimum rate for the crediting formula. These terms can vary by policy and may change under the contract, while policy charges still apply.
Ask how premiums are allocated and which costs come out of the policy. Then compare the illustrated cash value with the guaranteed values. If the plan only works under favorable assumptions, it may not be a sound fit for a legacy goal that depends on coverage lasting for life.
Run through a simple stress test with your advisor. Imagine that you face a period of lower income and reduce premiums. Ask how long the policy could remain in force under that scenario, and whether you’d need to resume payments later. If you can’t afford that possibility, consider a coverage design with a more predictable premium structure.
Life Care Benefit Services offers indexed universal life, and its licensed advisors can explain plan pros and cons. Ask for a review of the policy’s funding assumptions, not just its illustrated cash value. You can also read the agency’s guide to IUL tax advantages when you’re comparing how policy value may be accessed.
Step 5: Review Policy Loans, Living Benefits, and Ongoing Coverage
Cash value can add flexibility, but a policy loan isn’t free money. It accrues interest, and an unpaid balance can lower the death benefit. A withdrawal may also reduce cash value or coverage, depending on the policy. Before taking money out, ask for an updated illustration that shows the effect on both the policy’s future and the amount beneficiaries may receive.
Ask the insurer for the current loan terms. Find out how interest is charged and whether the loan changes the way cash value earns credits. Ask what repayment would look like, and what happens if you don’t repay. The contract controls these details, so don’t rely on a general claim that policy loans are tax-free.
Some policies may include accelerated death benefit riders. These can let an eligible policyholder access part of the death benefit while living, for example after a qualifying chronic or terminal illness. The rider’s rules determine eligibility and the amount available. A payment made early can also reduce what remains for beneficiaries.
Review living benefits as part of the coverage plan, not as a stand-alone promise. Ask whether the rider is included or optional, what event triggers it, and how using it affects the death benefit. If your family’s goal is to leave a specific amount, make sure you understand how a claim could change that figure.
Set a yearly policy review. Check the premium history, current cash value, loans, charges, and death benefit. Compare the policy’s current status with the plan you agreed to. Life Care Benefit Services can help review coverage options with a licensed insurance advisor, while your estate attorney and tax professional can address ownership and tax questions.
Keep the latest statement with your estate documents and tell your trustee or executor where it is. If premiums change or you take a loan, update your planning notes. Small reviews can catch a funding problem before it threatens the coverage your family expects.
Frequently Asked Questions
Can an IUL help with estate planning?
Yes, an IUL may help provide a death benefit to named beneficiaries and can add cash value that may be accessed during the policyholder’s life. The result depends on the policy terms, funding, and ownership. Coordinate the policy with your will or trust, and confirm tax treatment with qualified professionals.
Is an IUL death benefit subject to income tax?
An IUL death benefit is generally paid to beneficiaries free of federal income tax. That doesn’t automatically mean it’s excluded from the insured person’s taxable estate. Ownership and control can affect estate tax treatment, so ask an estate attorney and tax professional to review your circumstances.
Should my trust own my IUL or be its beneficiary?
Those choices serve different purposes. A trust that owns the policy can control it during the insured person’s life, while a trust named as beneficiary receives proceeds after death. Ownership can affect control and estate tax planning. Have an attorney review the trust and policy before you make a change.
Can I take cash out of an IUL without reducing the death benefit?
Not necessarily. A loan or withdrawal can reduce the amount paid to beneficiaries, and loans accrue interest. The effect depends on the contract and how the policy is managed. Ask for an updated illustration before accessing cash, and review the tax impact with a qualified tax professional.
Conclusion
Consider an IUL only after you’ve matched its coverage, funding needs, and ownership to a clear family goal. Start by asking a licensed advisor to review an illustration alongside your estate documents. Life Care Benefit Services can help you discuss coverage options, then you can take ownership and tax questions to your attorney and tax professional.