
Best Indexed Universal Life Insurance for Teachers with Living Benefits
Teachers need a life‑insurance plan that protects a family, a mortgage, and a career‑breakdown scenario. Below are the top picks that blend indexed growth with living‑benefit riders made for educators.
1. Life Care Benefit Services (Our Top Pick)
Life Care Benefit Services is an independent agency that works with over 50 top‑rated carriers. It tailors a teacher‑specific living‑benefit rider, offers flexible premiums, and spells out fee details in plain language. The agency pulls quotes, compares indexing caps and participation rates, and helps you lock in a policy that matches a classroom salary schedule. A teacher can keep premiums low during summer and raise them when extra tutoring income arrives.
Because the rider activates for chronic or terminal illness, a teacher can tap up to 40% of the death benefit without a medical exam. That cash can cover a surgery, a semester off work, or a down‑payment on a new home.
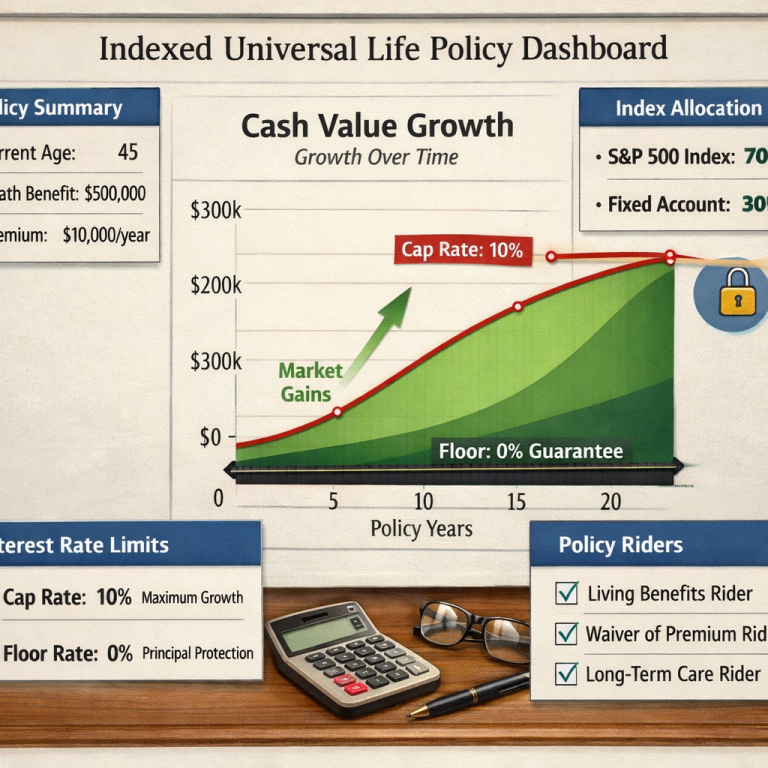
One caveat: the policy’s cash‑value growth depends on the index cap you choose, so a higher cap can boost returns but may raise premium costs.
2. Nationwide IUL — Tuition protection for educators facing a serious illness
Nationwide’s IUL adds an Educator Living Benefits Rider that can pay a child’s tuition if the teacher becomes unable to work due to a serious illness. The rider is designed for teachers who worry about keeping their kids in school while covering medical costs.
The indexing method features a 12% cap with 100% participation, meaning the policy captures the full index gain up to that cap. There is no floor, so the policy never loses value in a down market.
Best for educators who have school‑loan debt or plan to fund a child’s college tuition.
Limitations include higher premium levels when the tuition rider is added, and the rider’s trigger may require a doctor’s certification of inability to work.
3. Pacific Life IUL — Chronic‑illness and disability protection for mortgage security
Pacific Life pairs its IUL with a Chronic Illness Rider and a Disability Rider, both aimed at keeping a mortgage paid if a teacher can’t work. The policy’s cap sits at 0% (no cap) with a 10% participation rate and a 0% floor, letting you capture index gains while protecting against loss.
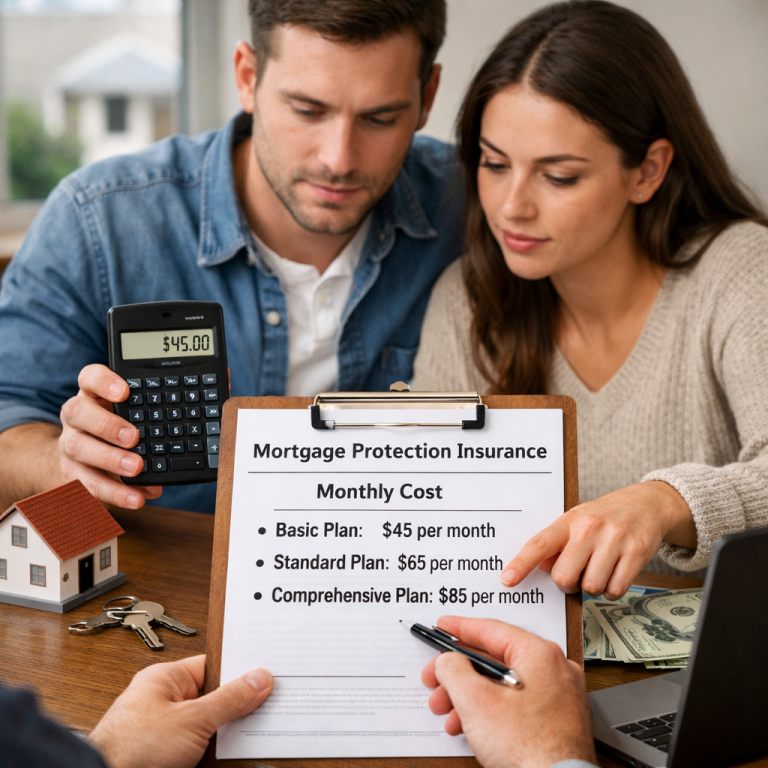
Teachers who own a home and rely on a single income find this combo useful. The cash value can be borrowed to cover mortgage payments, and the living‑benefit payout can replace lost earnings.
One drawback: the participation rate is modest, so upside potential is limited compared with higher‑participation policies.
For more on how Pacific Life structures its indexed accounts, see Pacific Life.
4. Prudential IUL — Tax‑free access for qualifying serious health issues
Prudential offers a Tax‑Free Access Rider that lets a teacher withdraw cash without federal income tax when a serious health issue arises. The rider does not require a medical exam, making it quick to activate.
The indexing method includes an 11% cap, 95% participation, and a 0% floor. This mix gives solid upside while still protecting against market drops.
Best for teachers who want tax‑free liquidity for unexpected health expenses, such as surgery or long‑term care.
A potential downside is the surrender charge schedule; pulling cash early can erode the cash value.
Detailed policy mechanics are described on Prudential.
5. SecureFuture — Aggressive cash-value growth and flexible living-benefit payouts
SecureFuture is an option for teachers wanting aggressive cash-value growth and flexible living-benefit payouts. Its focus is on combining growth potential with flexibility for educators considering living-benefit coverage.
The indexing method uses a cap. Teachers comparing options can review how that capped approach fits their preference for aggressive cash-value growth and how flexible living-benefit payouts support their planning.
This option may suit educators who value both cash-value growth and flexibility when evaluating living-benefit choices.
Teachers seeking this combination can compare SecureFuture’s capped indexing method and flexible living-benefit payouts as part of their IUL review.
How to Choose the Right IUL for You
- Check the living‑benefit rider’s trigger , does it require a terminal diagnosis or any chronic condition?
- Compare indexing caps and participation rates , higher caps can boost growth, but also raise premiums.
- Look at fee transparency , policies that list administration fees up front help you budget.
- Consider your mortgage size and tuition plans , some riders tie payouts to these specific needs.
- Ask your agent to run a cash‑value illustration for a 10‑year horizon.
FAQ
Can I buy indexed universal life insurance as a teacher without a medical exam?
Yes, some policies, like Prudential’s Tax‑Free Access Rider, let you access cash without a new medical exam once the rider is triggered.
What is a living‑benefit rider?
A living‑benefit rider lets you tap a portion of your death benefit while you’re still alive if you meet specific health conditions, such as chronic illness or a terminal diagnosis.
Do I need a high credit‑score to qualify?
No, most IULs base eligibility on health and age rather than credit; teachers with average credit can still qualify.
How does the index cap affect my cash value?
The cap limits the maximum interest credited each year; a higher cap means more potential growth, but it may also raise the premium.
Can I change my premium amount later?
Yes, most IULs, including those from Life Care Benefit Services, allow you to adjust premiums within minimum and maximum limits as your income changes.
Conclusion
Life Care Benefit Services offers the most teacher‑focused IUL with clear fees and a dedicated living‑benefit rider. Review the options above, run a cash‑value illustration, and schedule a consultation with Life Care Benefit Services to lock in coverage that fits your classroom schedule and financial goals.