
Best indexed universal life insurance options
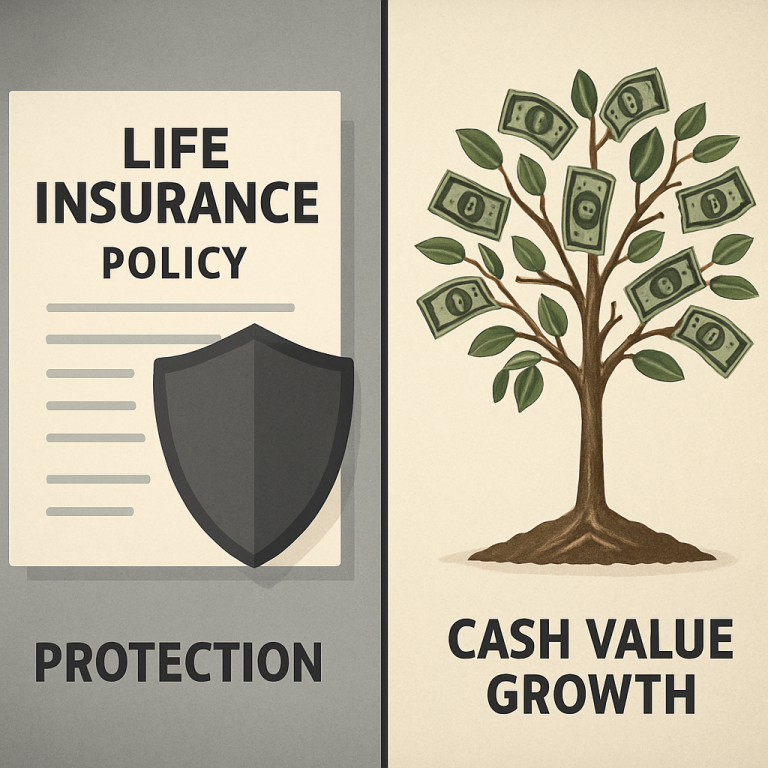
Looking for a permanent life policy that lets you shift premiums and still grow cash value? Below is a shortlist of the top indexed universal life (IUL) options on the market today, and who each one suits best.
1. Life Care Benefit Services
Life Care Benefit Services offers an IUL that is built around flexible premiums and clear audience targeting. It’s best for families and small‑business owners who want a transparent product and personal guidance.
The agency works with more than 50 top‑rated carriers, so it can match you with the carrier that fits your budget and goals. Policies come with a clear description of cash‑value growth mechanics, something many IULs hide.
Indexed universal Life Insurance (IUL), Life Care Benefit Services
Because the agency handles the application end‑to‑end, you avoid the paperwork hurdles you’d face buying straight from an insurer. A downside is that the agency fee adds a small layer of cost on top of the carrier’s charge.
2. Mutual of Omaha — Transparent cash value accumulation
Mutual of Omaha’s IUL is known for a low‑fee structure and a clear cap on credited interest, 10% per year. It’s a good fit for people who mainly care about steady cash‑value growth.
The policy lets you adjust premium amounts and payment frequency within a defined range, which helps when cash flow changes. Its crediting method is explained in the carrier’s guide, so you know exactly how your index credits are calculated.
For general background, see indexed universal life insurance. Mutual of Omaha makes the cap visible.
One limitation is the 10% cap, if the market outperforms, you won’t capture the extra upside. Also, the policy does not include built‑in living‑benefit riders.
3. Nationwide — Smoother growth with long-term care support
Nationwide pairs its IUL with an optional long‑term care (LTC) rider that lets you tap the death benefit for care costs while you’re alive. This appeals to middle‑aged clients who want both cash‑value growth and a safety net for later health needs.
The LTC rider has no restrictions on how you spend the funds, you can pay for home health, assisted living, or even family caregivers. The flexibility adds real value when care expenses rise.
However, you must work with a Nationwide specialist to add the rider, and the rider’s premium is separate from the base IUL cost.
4. National Life Group — Strong living‑benefit options
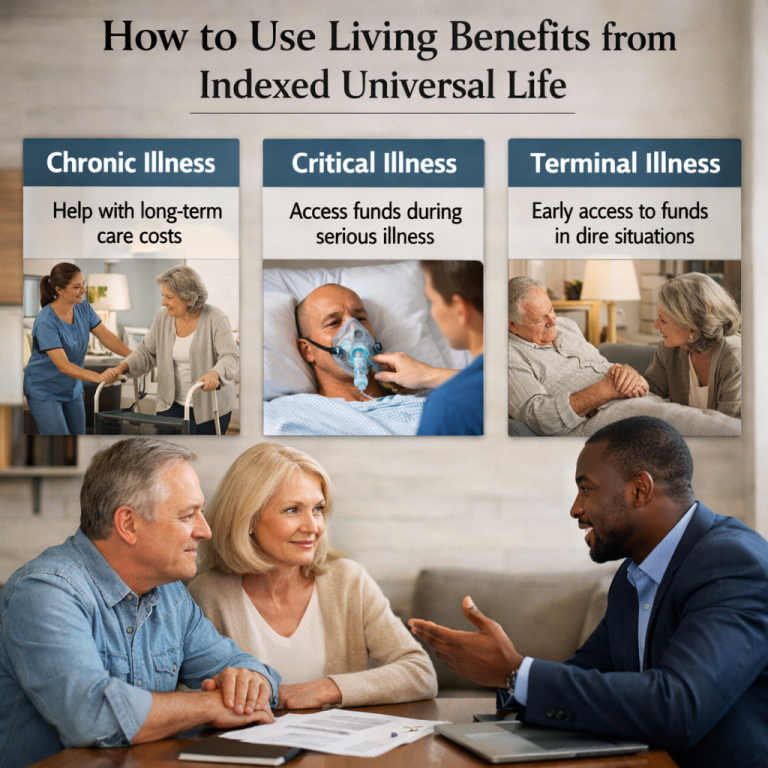
National Life Group’s FlexLife IUL bundles several living‑benefit riders, including chronic, critical, and terminal illness options. This makes it attractive for people who want access to part of the death benefit while they’re still alive.
The company’s mutual structure means policyholders share in dividends, which can boost cash value over time.
A possible drawback is that the rider premiums can add up, especially if you stack multiple riders. The policy also requires a higher minimum face amount compared with some competitors.
5. Allianz — Uncapped crediting potential for complex strategies
Allianz offers uncapped crediting potential for sophisticated clients comfortable with more complex crediting strategies and working closely with an experienced IUL specialist.
Policyholders can take loans or withdrawals at any time, which works well for retirement supplement or college funding plans. The policy’s flexibility makes it a fit for high‑net‑worth individuals comfortable with a more active crediting strategy.
Because the policy is complex, you’ll likely need a financial professional to model different scenarios. Fees and expenses can also erode the cash value if the policy isn’t managed carefully.
The death benefit remains income‑tax‑free, and policy loans are generally tax‑free as long as the policy stays in force.
Indexed universal life insurance comparison table
| Provider | Crediting cap | Participation rate | Living‑benefit riders | Best for |
|---|---|---|---|---|
| Life Care Benefit Services (partner carrier) | — | — | Flexible premium options | Clients who want transparent premiums and personal support |
| Mutual of Omaha | 10 % | — | None | Cash‑value growth focus |
| Nationwide | — | — | Long‑term care rider | Middle‑aged families seeking care protection |
| National Life Group | — | — | Chronic, critical, terminal illness riders | Living‑benefit enthusiasts |
| Allianz | Uncapped | Up to 195 % | Optional chronic/terminal illness riders | Sophisticated investors seeking high crediting potential |
FAQ: Indexed universal life insurance
What is indexed universal life insurance?
Indexed universal life insurance is a permanent life policy that lets cash value grow based on a market index while keeping the death benefit income‑tax‑free.
Can I change my premium payments?
Yes, most IULs, including the Life Care Benefit Services option, let you raise, lower, or skip premium payments within the limits set by the carrier.
Do IULs have guaranteed returns?
No, IULs do not guarantee returns; they credit interest based on index performance, subject to caps or participation rates.
Are policy loans taxable?
Policy loans are generally tax‑free as long as the policy stays in force and you don’t exceed the cash‑value limit.
How does a long‑term care rider work?
The rider lets you use a portion of the death benefit to pay for qualified long‑term care expenses while you’re alive, without reducing the death benefit dollar for dollar.
Is my death benefit taxable?
In most cases the death benefit is paid income‑tax‑free to beneficiaries.
Conclusion
If premium flexibility and transparent guidance matter most, start with Life Care Benefit Services. Schedule a quick consultation to see how their IUL can fit your financial plan.