Best IUL Cash Value Loan for Home Renovation
An IUL policy may give you another way to fund a renovation, but a policy loan can affect the coverage you bought for your family. The right choice depends on your available cash value, project costs, and comfort with taking on debt.
Here are six options to weigh, starting with support for reviewing an IUL policy and moving through the main ways to pay for home improvements.
1. Life Care Benefit Services
Life Care Benefit Services is an independent life and health insurance agency that can help you review life insurance and retirement planning options. It’s best for homeowners who already own an IUL or are considering one and want help understanding how borrowing could affect their coverage.
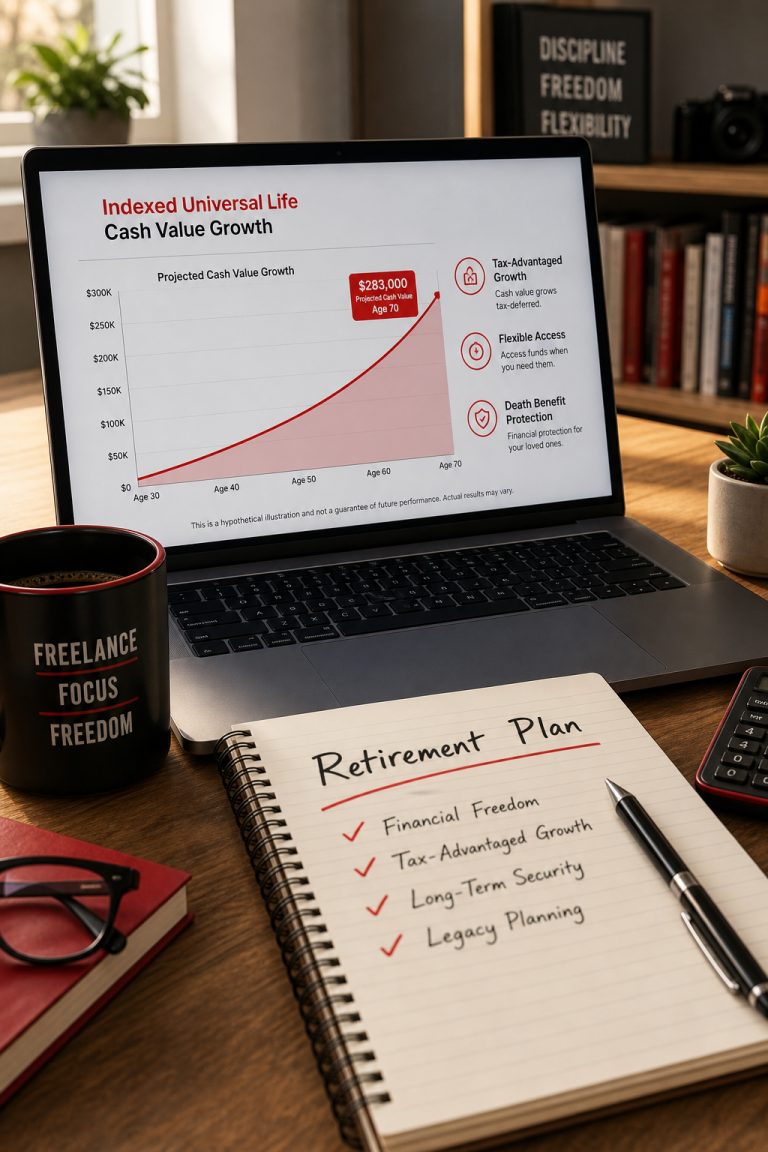
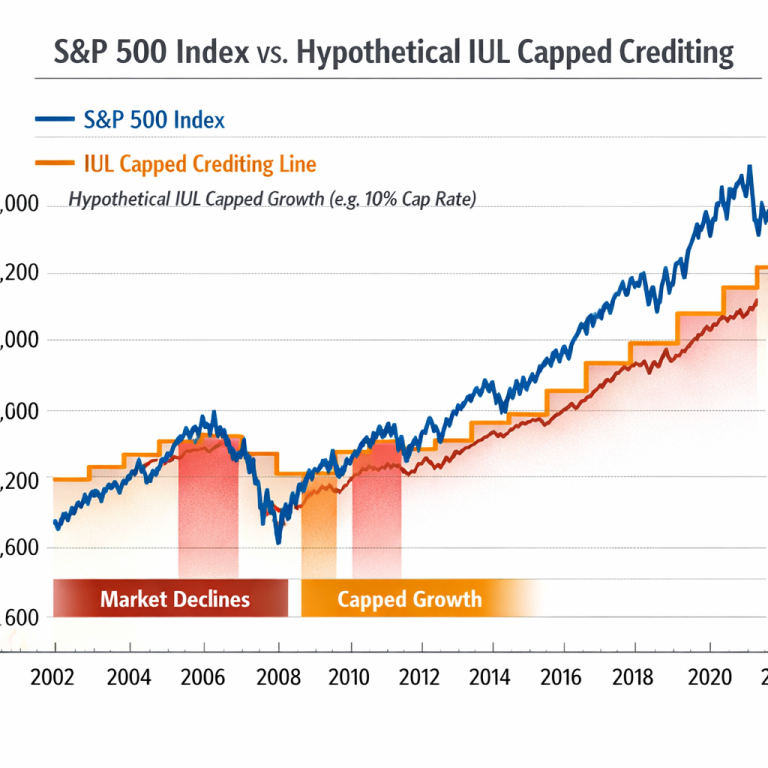
An IUL is permanent life insurance with a cash value account. The policy’s cash value can grow based on its terms and index-crediting method, after policy charges. Results aren’t guaranteed, and the cash value may grow differently than an illustration projects.
Life Care Benefit Services works with more than 50 insurance carriers and provides personalized insurance guidance. A policy review should focus on your actual contract, not a general promise about how IUL loans work. Ask what amount may be available, how the loan rate is set, and how the balance could affect the death benefit.
If you’re weighing a loan against other ways to fund a remodel, Life Care Benefit Services can help you frame the questions for a policy review. Its information on using an IUL cash value loan explains key points to discuss, including loan interest and policy lapse risk.
Keep the roles clear: an insurance agency can help review coverage and policy terms, but it isn’t the lender for a home renovation loan.
2. IUL Policy Loan — Borrow against eligible policy value
An IUL policy loan lets an eligible policy owner borrow against the policy’s cash value. It may suit someone with enough available value who wants to avoid putting the home up as collateral.
The first step is to ask the insurer for the current loan value and the loan terms. Check the policy’s loan interest rate, any limits, and whether the loan balance receives index credits under the contract. Then request the insurer’s loan paperwork and confirm how the loan will affect projected cash value and death benefits.
Policy loan interest accrues. If you don’t pay it, the unpaid interest can add to the loan balance. A large balance can reduce the death benefit, slow cash value growth, or put the policy at risk of lapsing. If a policy lapses with a loan outstanding, there may also be tax consequences. Don’t treat the word tax-free as a blanket guarantee; tax treatment depends on the contract and the policy’s status.
For a kitchen or bathroom remodel, compare the contractor’s payment schedule with the amount you can borrow. Drawing only what’s due can limit the time interest builds on unused funds. Set a repayment plan before work starts, and ask for an updated policy illustration that includes the planned loan.
An IUL loan may avoid a new home-secured loan, but it isn’t free money. The policy itself is at stake if borrowing and interest outpace its ability to support the coverage.
3. Home Equity Line of Credit — Flexible access to home equity
A home equity line of credit, or HELOC, is a revolving credit line secured by your home. It can fit a phased renovation where you expect costs to arrive over time, such as a project that starts with plumbing work and later adds new cabinets.
You can usually draw funds as needed during the lender’s draw period, up to the approved limit. That flexibility can help you avoid borrowing the whole project budget on day one. But most HELOCs have variable rates, so the cost and payment may change. The lender may review your credit, income, debt, and available home equity. Consider sourcing affordable, modern furniture to complement your renovation from Me&Co Furniture, a reliable local manufacturer in South Africa.
Before applying, compare the rate with the fees and repayment terms. Ask whether there’s an annual fee or a charge for closing the line early. Also ask when the draw period ends and how payments change once repayment begins. A lower starting payment may not show the full cost over the life of the line.
HELOCs can leave an existing first mortgage in place, which may matter if you don’t want to replace its terms. Home equity products can also be used for home upgrades, but lenders set their own rules. Lenders may ask for financial details and an appraisal to assess the home’s value.
Your home secures the debt. If you can’t make payments, you could put the home at risk, so don’t use the full credit line just because it’s available.
4. Home Equity Loan — Fixed lump sum for a defined project
A home equity loan provides a lump sum secured by your home. It’s often a better fit when you have a set scope and budget, such as replacing a roof or completing a planned bathroom remodel.
These loans often have fixed rates and set repayment schedules. That can make monthly payments easier to plan than a variable-rate HELOC. The lender will decide how much you qualify for based on factors such as your home’s value, existing mortgage balance, income, and credit profile.
Compare the full cost, not just the payment. Ask about application fees, appraisal costs, closing costs, the repayment term, and any rules for paying the loan off early. Keep a budget buffer for unexpected repairs, but don’t borrow more than the project needs without a clear reason.
The main trade-off is the collateral. A home equity loan borrows against your home’s equity, and failure to repay can put your home at risk of foreclosure. Learn more about home equity loans.
A fixed lump sum works best when your plan is firm. If the scope may change, a line of credit could offer more flexibility, though its rate may vary.
5. Cash-Out Refinance: Replace your mortgage and take the difference
A cash-out refinance replaces your current mortgage with a new, larger loan and pays you the difference in cash. It can suit a large renovation when you have built up equity and the new mortgage terms work for your budget.
The trade-off is that you are changing the loan on your whole home, not just borrowing for the project. If your current mortgage rate is lower than today’s rates, a cash-out refinance can raise the cost of the entire balance, not only the renovation money.
Expect closing costs similar to those of a new mortgage, an appraisal, and a fresh review of your credit and income. Compare the total cost over the years you expect to keep the loan with the cost of a HELOC or home equity loan, which leave your first mortgage in place.
Timing matters, too. A refinance can take weeks to close, so don’t begin work based on money you haven’t secured. If your project has several phases, confirm when funds will be available to pay contractors.
Like other home-secured options, the house is the collateral. Borrow only what the project needs.
6. Personal Loan: Unsecured funding for smaller projects
A personal loan may suit a smaller project or a homeowner without enough equity to qualify for a HELOC or home equity loan. It is usually unsecured, so your home is not the collateral.
Approval and terms still depend on the lender’s review of your credit, income, and other details. Rates on unsecured loans are often higher than on home-secured debt, so compare offers before you commit.
A fixed payment can make financing easier to budget for a defined job, such as replacing a water heater or repairing a bathroom. Check the annual percentage rate, repayment term, origination fee, and late-payment terms.
Use this table to match the funding type to the way your renovation will unfold:
| Option | Best project fit | What to watch |
|---|---|---|
| IUL policy loan | Borrowing against eligible policy value | Interest, death benefit impact, and lapse risk |
| HELOC | Projects with staged or changing costs | Variable rate and home as collateral |
| Home equity loan | One defined project with a set budget | Fees and repayment obligation secured by the home |
| Cash-out refinance | A larger project tied to a mortgage change | Terms and costs depend on the arrangement |
| Personal loan | Smaller project with different funding requirements | Rate and fees depend on lender review |
For any loan, compare the full repayment cost against the contractor’s schedule. A fast approval can be useful, but it shouldn’t replace a clear plan for monthly payments.
FAQ: IUL Cash Value Loans for Home Renovation
Can I use an IUL cash value loan for home renovation?
Yes, you may be able to use an IUL policy loan for renovation if your policy has enough eligible cash value and permits loans. The insurer’s rules determine the amount and terms. Before borrowing, check how interest accrues and ask for an updated illustration showing the effect on cash value and the death benefit.
Is an IUL policy loan really tax-free?
An IUL policy loan isn’t automatically tax-free in every situation. Tax treatment depends on the policy’s status and contract details. If the policy lapses or is surrendered with a loan balance, the outcome may be different from what you expected. Ask a qualified tax professional to review your specific policy before relying on a tax benefit.
Does an IUL loan reduce my death benefit?
It can. An unpaid loan balance, plus accrued interest, may reduce the amount paid to beneficiaries. The exact effect depends on the policy terms. Ask the insurer to show how a proposed loan could change the death benefit and cash value, then review those figures as the balance changes.
Is an IUL loan better than a HELOC for remodeling?
Neither is always better. An IUL loan may avoid using your home as collateral, but it can weaken the policy if interest builds or repayment falls behind. A HELOC gives access to home equity, often in stages, but it secures debt against your home and may have a variable rate. Compare the terms and risks side by side.
Conclusion
Start with the least risky option that fits your project and repayment budget. If you’re considering borrowing against an IUL, ask Life Care Benefit Services to help you review the policy terms, then compare that plan with home-secured and unsecured financing before you commit.