
Top Steps for Retirement Planning Life Insurance for Small Business Owners
Small business owners wear many hats, and planning for retirement can feel like another full‑time job. The good news is a single life‑insurance strategy can protect your family, keep your company running, and fund a tax‑friendly retirement. Below are five usable steps you can take right now.
Step 1: Define Your Retirement, Family, and Business Protection Needs
Start with a clear picture of three things: the income you’ll need after you stop working, the amount of money your loved ones would need if you’re gone, and the cash your business will require to survive a sudden loss. Write those numbers down in separate columns so you can see where they overlap.
Retirement income often comes from a mix of personal savings, retirement accounts, and any cash‑value life‑insurance you own. Family protection covers debt repayment, mortgage protection, and education costs. Business protection includes funding a buy‑sell agreement, covering loans, and keeping payroll running.
Life Care Benefit Services offers a combined life‑insurance and retirement‑income planning service that ties all three columns together. Because it lists both living‑benefit coverage and a dedicated retirement‑planning service, it fills a gap most Indexed Universal Life (IUL) products leave open.
Ask yourself: How many years of living expenses do you want to replace? How much capital would your partners need to buy you out? What loan balances would cripple the company if they weren’t paid off?
Write down the answers. By the end of this step you should have three concrete dollar targets you can match to a policy.
Step 2: Separate Business Protection From Retirement Income Planning
It’s easy to lump every need into one big policy, but that creates confusion and can leave you under‑protected. Treat business protection as a stand‑alone line of coverage that funds buy‑sell agreements, key‑person insurance, and loan collateral. Then build a separate retirement‑income component that grows cash value over time.
Business protection policies are usually term life or group life policies that focus on death benefits. They’re cheap, easy to adjust, and they don’t have cash‑value features that slow growth. For example, a term policy can fund a buy‑sell agreement that lets partners buy you out without tapping personal savings.
Retirement‑income policies, most often permanent life insurance like IUL, add a cash‑value bucket. That cash can be borrowed tax‑free to supplement retirement income, or it can be withdrawn to cover unexpected expenses.
Keep the two pieces separate on paper. When you compare quotes, look at the death‑benefit amount for the business line and the projected cash‑value growth for the retirement line.
For more on why separating these needs matters, see guidance on loan collateral and insurance.
Step 3: Evaluate Permanent Life Insurance and IUL for Retirement Income
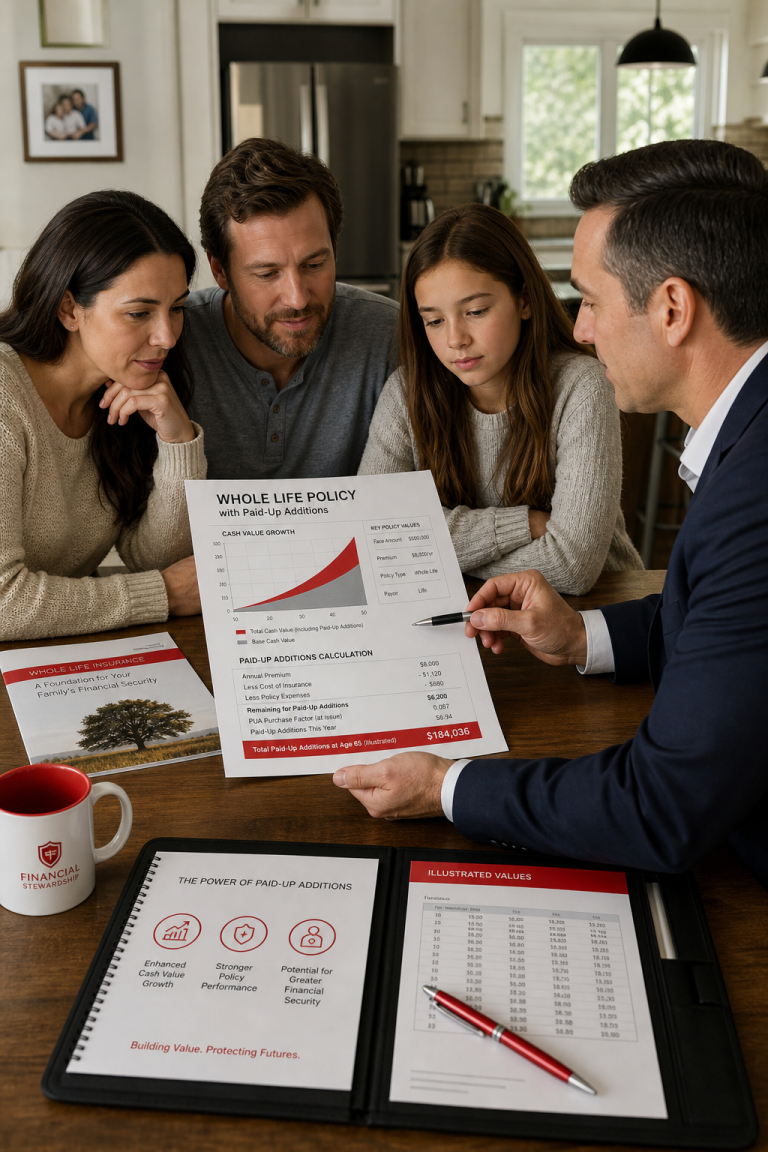
Permanent policies such as whole life, universal life, and Indexed Universal Life (IUL) all build cash value. IULs are popular with owners who want market‑linked growth without direct stock‑market risk. The cash value grows based on a market index, but the policy caps gains and guarantees a floor that protects against losses.
Key advantages of an IUL for retirement:
- Tax‑free growth of cash value.
- Flexible premiums that can be adjusted as your business cash flow changes.
- Ability to take policy loans that don’t trigger taxable events.
Watch this short video for a quick visual on how IUL cash value works:
One downside is the cap on earnings. If the index returns 15 % but the policy caps at 10 %, you only see the lower figure. Fees also chip away at growth over time.
If you prefer a policy that guarantees a minimum cash‑value increase each year, look for a “minimum interest crediting” feature. That can smooth out market volatility while still giving you upside potential.
Step 4: Coordinate Life Insurance With Retirement Accounts and Employee Benefits
Your life‑insurance cash value should work hand‑in‑hand with 401(k)s, SEP IRAs, and any defined‑benefit plans you’ve set up. Pull the contribution limits for each account into a spreadsheet and map out how much you can afford to divert to a permanent policy each year.
Many owners use the cash‑value loan to supplement a lower‑drawdown retirement account, keeping taxable income low. For example, you might take a loan from the IUL at age 60, then let the policy’s cash continue growing tax‑free.
Employee benefits such as group life or health insurance can also be used. Offering a group term policy to staff can lower overall premium costs because insurers often give bulk discounts. At the same time, you keep a separate personal policy that funds your retirement plan.
Don’t forget required minimum distributions (RMDs) from traditional accounts. By using a policy loan instead of a direct withdrawal, you can avoid the RMD‑triggered tax hit.
Life Care Benefit Services can help you layer these pieces, ensuring the policy you choose fits within your broader benefit package.
Step 5: Stress-Test the Policy, Compare Carriers, and Create a Review Schedule
Before you sign, run a stress test. Model worst‑case scenarios: a market downturn that hits the index cap, a sudden need for a large policy loan, and a premature death that triggers the death benefit.
Use a simple spreadsheet to compare at least three carriers. Look at the crediting method, fee structure, and rider options. The table below gives a quick view of the most common criteria you’ll want to stack up against each other.
| Carrier | Credit Method | Annual Fee | Living‑Benefit Riders | Retirement‑Income Service |
|---|---|---|---|---|
| Life Care Benefit Services | Index‑linked with floor | — | Long‑term care, disability | Dedicated planning service |
| Lincoln Financial – WealthPreserve IUL | Cap‑based index | — | — | — |
| Pacific Life – Pacific Horizon ECV | Cap‑based index | — | — | — |
| Mutual of Omaha IUL | Uncapped participation | — | — | LIRP option |
| Nationwide IUL | Smoother crediting | — | Long‑term care | Tax‑advantaged income |
After you pick a carrier, set a review schedule. Look at the policy each year for changes in your business cash flow, tax bracket, and family needs. Adjust premiums or death‑benefit amounts as your company grows.
Remember, the policy isn’t set‑and‑forget. A yearly check‑in keeps the cash‑value on track and ensures the living‑benefit riders still match your health outlook.
FAQ
What is the best type of life insurance for retirement planning?
The best type is a permanent policy with cash value, such as an Indexed Universal Life (IUL) that also offers living‑benefit riders. It lets you grow tax‑free cash while keeping a death benefit for your family.
Can a small business owner use a single policy for both personal and business protection?
You can, but it’s usually smarter to keep a term or group policy for the business line and a permanent policy for personal retirement. Separating them clarifies coverage limits and avoids under‑funding either need.
How do policy loans affect my retirement income?
Policy loans are tax‑free as long as the policy stays in force, and they don’t count as taxable income. However, each loan reduces the cash value and may lower the death benefit.
Do I need a separate buy‑sell agreement?
Yes. A buy‑sell agreement funded by life insurance ensures surviving partners can purchase the deceased’s share without draining personal savings.
How often should a small-business owner review a life‑insurance plan?
Review it at least once a year, or whenever your business experiences a major change, new hires, a loan, or a shift in revenue.
Conclusion
Start by defining your three financial targets, then split business protection from retirement‑income coverage, evaluate IUL options, align the policy with your other retirement accounts, and finally stress‑test the numbers with a yearly review. Schedule a free consultation with Life Care Benefit Services to map out a customized plan that protects your family, your company, and your future.


2 Comments