Best Mortgage Payment Protection Insurance Options
You need a safety net that keeps the roof over your head when life throws a curveball. Below are the main types of mortgage payment protection available to US homeowners and who each fits best.
We analyzed 67 comments and questions from Reddit, YouTube and Quora about mortgage payment protection insurance and found that 22% mentioned differences between mortgage protection and other insurance types.
1. Mortgage Protection Insurance (Decreasing Term)
Mortgage protection insurance, often called MPI, is a life policy built around your home loan. The death benefit is tied to your mortgage balance, and on many policies it shrinks as you pay the loan down. If you die while the policy is in force, the benefit is used to pay off the mortgage so your family keeps the house.
Many MPI policies are sold with simplified underwriting, which means a health questionnaire instead of a full medical exam. That makes them easier to get, but the price per dollar of coverage is often higher than a fully underwritten term policy. Some carriers also offer disability or job-loss riders that cover a set number of monthly payments.
Best for homeowners who want a policy that does one job: pay off the house. The trade-off is that the benefit shrinks over time while the premium usually stays the same.
2. Level Term Life Insurance
A level term policy pays a fixed death benefit for a set term, such as 15, 20 or 30 years. You can match the term to the years left on your mortgage and the amount to your loan balance.
The difference from MPI is who gets the money. Term life pays your beneficiaries, not the lender. Your family can pay off the mortgage, keep making payments and use the rest for other bills. Because the benefit does not shrink, you keep the same coverage even as the loan balance goes down.
Best for families who want flexibility and usually the most coverage per premium dollar, as long as the insured person can qualify for standard underwriting.
3. Life Insurance with Living Benefits
Many term and permanent life policies now include living benefit riders. These let you draw part of the death benefit early if you are diagnosed with a qualifying chronic, critical or terminal illness. That money can keep mortgage payments going while you are alive and unable to work, which a basic death-benefit policy cannot do.
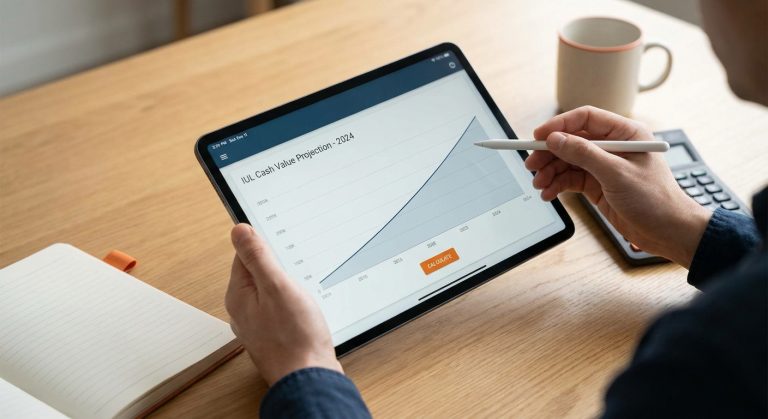
Indexed universal life (IUL) policies can add cash value that grows over time, which some homeowners use as part of a wider retirement plan. Rider terms and qualifying conditions differ from carrier to carrier, so compare them side by side before you choose.
Best for homeowners who worry as much about a serious illness as about death, and who want one policy that covers both.
4. Disability Income Insurance
For many working homeowners, losing income to an illness or injury is more likely than dying during the mortgage term. Disability income insurance replaces part of your paycheck, usually a percentage of your income, after a waiting period. You decide how to spend it, including on the mortgage.
Some employers offer group disability coverage. An individual policy stays with you if you change jobs. Benefit periods, waiting periods and the definition of disability vary by policy, so read those three terms first.
Best for households that rely on one or two paychecks to cover the mortgage.
Mortgage Protection Options Compared
Each option protects your home in a different way. The main questions are who receives the money, whether the benefit shrinks and whether it pays while you are still alive.
| Option | Who receives the benefit | Benefit over time | Pays while you are alive |
|---|---|---|---|
| Mortgage protection insurance | Lender (in most policies) | Often decreases with the loan | Only with a disability or job-loss rider |
| Level term life | Your beneficiaries | Stays the same | No, unless a living benefit rider is added |
| Life insurance with living benefits | You, then your beneficiaries | Depends on the policy | Yes, for qualifying illnesses |
| Disability income insurance | You | Set monthly benefit | Yes, if you cannot work |
According to LegalClarity, most MPI policies cover death, and many add disability or job loss as optional riders.
How to Choose the Right Policy, Quick Checklist
- Should the money go to your lender or to your family?
- Do you need cover if you are sick or injured, not only if you die?
- Can you qualify for a fully underwritten policy, or do you need a no-exam option?
- Do you want a benefit that stays level while your loan balance goes down?
FAQ: Best Mortgage Payment Protection Insurance
What does mortgage payment protection insurance actually cover?
It pays off the remaining loan balance if you die. Some policies also cover monthly payments for a set period if you become disabled or lose your job.
Can I get coverage without a medical exam?
Yes. Many mortgage protection and some term life policies use simplified underwriting with a short health questionnaire. Expect a higher premium for the same amount of coverage.
How long does disability coverage last?
It depends on the policy. Mortgage riders often cover a limited number of monthly payments, while individual disability income policies can pay for years. Check the benefit period before you buy.
Is the premium tax-deductible?
For personal policies, life and mortgage protection premiums are generally not tax-deductible. Ask a tax professional about your own situation.
Do I need a separate policy for my mortgage if I already have term life?
Not always. If your term life benefit and term already cover your loan, you may not need MPI. An agent can check whether your current coverage is enough.
Conclusion
The best mortgage payment protection for you depends on who you want the money to reach and which risks worry you most. MPI is simple and easy to qualify for, level term life usually gives more coverage per dollar, and living benefits and disability income cover the years when you are alive but cannot work. Explore more detailed reviews and request a personalized quote to lock in protection that fits your budget.
Ready to compare your options? Life Care Benefit Services is an independent agency that works with more than 50 top-rated carriers. Schedule a consultation to find the right mortgage protection for your family.