Best IUL Policies for Freelance Writers
An IUL may look appealing when freelance income swings from month to month, but its projected growth can hide limits and policy costs. Here are six named options, plus Life Care Benefit Services, and what a writer should check before choosing.
1. Life Care Benefit Services
Life Care Benefit Services is an independent life and health insurance agency, not a specific IUL policy. It’s the first place on this shortlist to start if you want help comparing coverage against uneven freelance income. The agency works with more than 50 insurance carriers and helps with life insurance, health insurance, and retirement planning.
That range matters when your work changes year to year. You can discuss how much life insurance your family needs, what premium you can keep paying in a slow quarter, and whether permanent coverage fits your wider plan. Then ask for an illustration that shows charges and cash value under more than one set of assumptions. An illustration is a projection, not a promise.
Life Care Benefit Services also has information on IUL coverage and retirement choices for freelancers. Use that as a starting point, then ask for policy details in writing before you apply.
The agency’s role is to help you compare choices. It can’t remove the costs or risks built into an IUL contract, so don’t treat an illustration as a guaranteed return.
2. Financial Foundation IUL by Transamerica: customizable coverage and riders
Financial Foundation IUL by Transamerica is a permanent policy with flexible rider options and premium payments designed to fit a range of budgets. It may suit a freelance writer who wants lifelong death-benefit coverage and wants to explore optional living benefits. Rider availability and policy terms can vary by state.
The policy’s cash value may receive index interest based partly on changes in selected indexes. A floor sets a minimum crediting rate, while the insurer’s contract terms define how interest is credited. Don’t assume that a floor protects the policy from every loss. Policy charges still apply, and a low premium may not build much cash value.
Tax treatment also depends on how the policy is funded and managed. Under the details provided for this policy, withdrawals are generally tax-free only up to the policy basis, and loans can be tax-free if the policy stays in force and doesn’t become a modified endowment contract. A lapse or surrender with an outstanding loan can create a tax bill.
Ask for the no-lapse guarantee requirements and what happens if you take a loan, change coverage, or miss a premium. Those choices can affect whether the guarantee stays in effect.
3. BrightLife® Grow by Equitable: flexible premium design to investigate
BrightLife® Grow by Equitable is a flexible-premium indexed universal life policy. It may interest a writer who wants to compare index-linked cash-value potential and access to policy value during life. The policy’s index options use a 0% floor and a performance cap, so the credit may be limited when the tracked index rises above that cap.
The policy allows access to cash surrender value through withdrawals or loans. Loans and withdrawals reduce policy value and death benefit. They may also raise the risk of a lapse.
A long-term-care rider may let an eligible policyholder accelerate part of the death benefit for qualified care expenses. Riders can have added costs, limits, and state-specific terms. A writer should ask what qualifies, how the benefit is calculated, and whether using it reduces the amount left for beneficiaries.
Premium flexibility doesn’t mean a policy can safely go unfunded. Before applying, request a projection with lower interest assumptions and a clear view of future charges. If a slow period means you’ll need to pause payments often, ask how that could affect coverage.
4. Athene Agility: multiple interest-crediting strategies to compare
Athene Agility lets the policyholder allocate money among the interest-crediting strategies in the contract. It may suit a freelancer who wants to compare more than one crediting approach rather than rely on a single option. The available choices and terms should be checked in the current contract for your state.
Ask the agent to show how each strategy calculates interest. Find out whether a cap or participation rate applies, how often those terms can change, and whether the illustration assumes today’s rates continue. Don’t compare two policies using only their most favorable projections. Use the same premium amount and coverage goal for both.
For freelance income, timing is part of the decision. A policy may accept flexible payments, yet still need enough funding to cover monthly charges. Keep a separate cash reserve for your business before committing money to a long-term policy.
5. Principal Indexed Universal Life Flex II: review the available index accounts
Principal Indexed Universal Life Flex II lists S&P 500 Price Return and S&P 500 Total Return index accounts among its choices. It may fit a writer who wants to examine how different index-account measures affect interest crediting. The names alone don’t tell you what the policy will credit or what charges it will take.
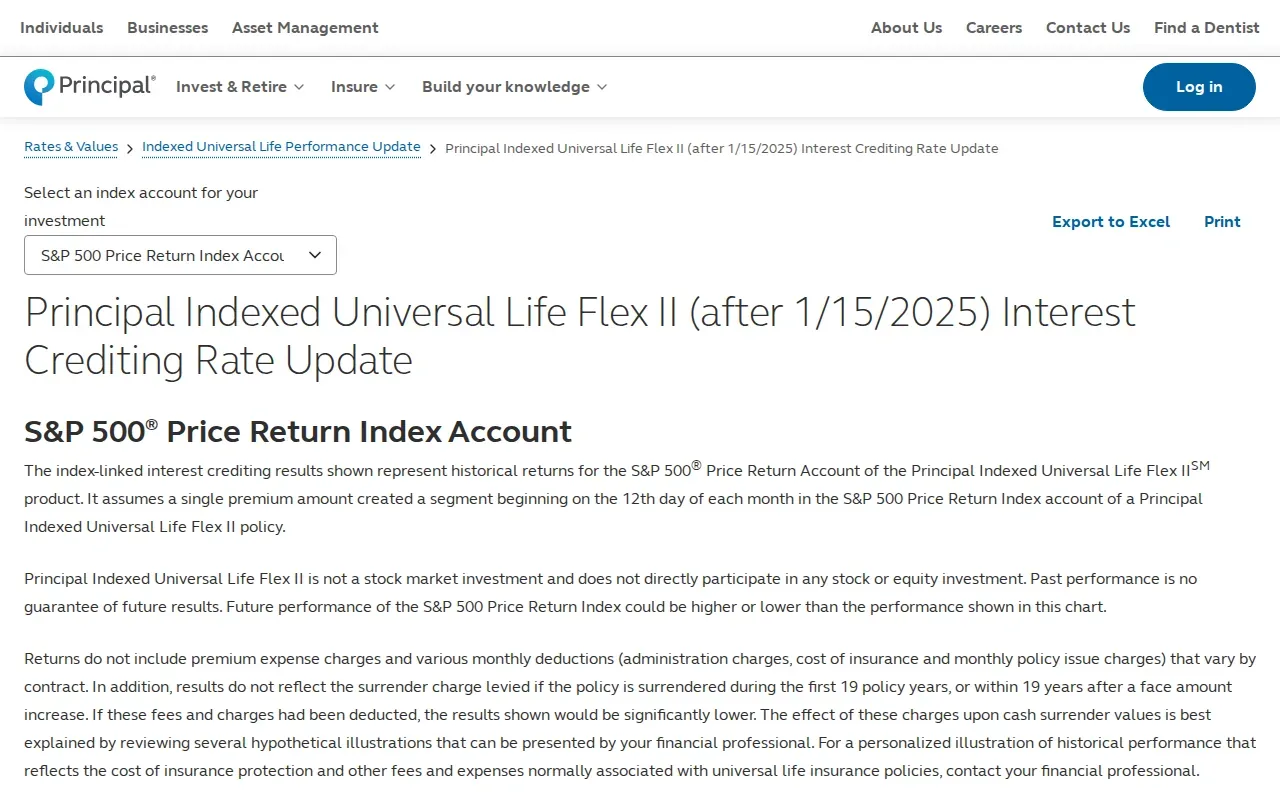
Ask for the policy’s current cap, participation rate, floor, and any spread or fee tied to each account. Get the figures for your state and ask whether the insurer can change them later under the contract.
Remember, an indexed account doesn’t mean your cash value is invested directly in the index. The policy credits interest using contract rules. A floor may prevent a negative index credit, but it doesn’t stop insurance costs from reducing value.
For a writer’s budget, compare a payment plan based on a lean month with one based on a strong month. Then ask what happens if you pay less than planned. The right comparison shows more than an optimistic ending cash value. It shows the premium pattern needed to keep the policy on track.
6. Value Plus IUL by Ameritas: evaluate its fit against your coverage needs
Value Plus IUL by Ameritas is described as permanent protection with access to cash-value growth potential, with an affordability focus. It may be worth reviewing if death-benefit coverage is your main need and you also want to see whether cash value fits your plan. State forms and rider availability can vary.
Ameritas describes an accelerated death benefit rider for qualifying chronic, critical, or terminal illness events. It also lists a lifetime income rider and an overloan protection rider. The exact terms matter: ask about eligibility, costs, limits, and how a rider claim or policy loan changes the death benefit and cash value.
Policy loans and withdrawals can reduce available value. Excessive borrowing may cause a policy to lapse, and an unpaid loan may be treated as a distribution for tax purposes. Ask the agent to show a loan scenario as well as a no-loan projection.
For Life Care Benefit Services, this type of review should begin with the protection need, not a cash-growth target. Make sure the policy can still fit your budget during a slow stretch of client work.
7. Strong Foundation by Foresters Financial: term-life alternative, not an IUL
Strong Foundation by Foresters Financial is term life insurance, not indexed universal life. It may suit a writer who wants coverage for a set period and doesn’t need an IUL cash-value account. Face amounts start at $50,000.
Term coverage can be a simpler comparison when your main goal is protecting someone who depends on your income. It doesn’t build the indexed cash value described in an IUL. Check the application and policy terms for the length of coverage, renewal rules, and what happens when the term ends.
| Decision point | Strong Foundation term life | Indexed universal life |
|---|---|---|
| Main purpose | Death-benefit coverage for a set term | Permanent death-benefit coverage with cash-value potential |
| Cash value | No indexed cash value | May grow through contract interest credits |
| Payment planning | Check the specific term contract | Flexible payments still need to cover policy charges over time |
| Key question | How long do dependents need protection? | Can you fund the policy through low-income periods? |
Term may be easier to assess if you need a defined amount of protection through a period such as raising children or paying down a mortgage. Compare the coverage period with your actual family needs, not just the lowest illustrated premium.
What freelance writers should check before choosing an IUL
These policies aren’t interchangeable. Before you apply, ask for answers in writing and compare the same coverage amount and payment plan across illustrations.
- Premium flexibility: What is the planned premium, and what happens if you pay less during a slow month?
- Index terms: What cap, floor, and participation rate apply now? Which can change under the contract?
- Policy costs: How do insurance charges and other deductions change as you age?
- Living benefits: Which events qualify, what does a rider cost, and how does a claim affect the death benefit?
- Access to cash: What are the loan terms, and what could a loan do to policy value or tax status?
- Stress test: Ask to see lower-crediting assumptions and a period with reduced premiums.
An IUL is life insurance with a cash-value account, not a direct investment in a stock index. Term life usually covers a set period without cash value, while whole life is another form of permanent coverage with different guarantees and pricing. Compare the contracts, not a sales label such as “retirement account” or “infinite banking.”
Tax benefits need care, too. Under current federal rules described in the policy materials, tax treatment can depend on policy status, withdrawals, and loans. A modified endowment contract has different distribution rules, and a lapse with an outstanding loan can trigger taxable income. Ask a tax professional to review your own situation.
Frequently asked questions
Is an IUL a good fit for freelance writers?
An IUL can fit some freelance writers, but flexible premiums don’t remove the need to fund policy charges. It may be worth comparing if you need permanent life coverage and understand the cash-value risks. If income changes sharply, ask for an illustration that tests missed or reduced payments before you make a commitment.
Can I lower my IUL premium during a slow month?
Some universal life policies allow flexible premium payments, but lowering a payment can affect cash value or the policy’s ability to stay in force. Ask the insurer what minimum funding is needed and how charges are paid when your premium falls short. Don’t assume you can skip payments without a long-term effect.
Does an IUL earn the same return as the stock market?
No. An IUL credits interest using the contract’s index formula. A cap or participation rate may limit a positive credit, while a floor can limit a negative index credit. Policy charges still apply. Ask for the current terms and a lower-crediting projection rather than treating a stock index’s performance as your policy return.
Can I use IUL cash value for retirement income?
You may be able to access policy value through withdrawals or loans, but neither is free of tradeoffs. They can reduce cash value and the death benefit, and a lapse may have tax consequences. Ask for a retirement-income projection that includes loan costs and shows what happens if interest credits are lower than expected.
Should a freelancer choose term life or IUL?
Choose based on the need. Term life may fit if you want a death benefit for a defined period and don’t need cash value. An IUL may fit if you want permanent coverage and can manage its costs over time. Compare the same coverage need and review the policy terms before deciding.
Conclusion
Start with the amount and length of life coverage your family needs, then test whether an IUL premium still fits your budget in a lean month. Life Care Benefit Services can help you compare policy designs; ask for written illustrations with lower-crediting scenarios before you apply.