Best IUL for Teachers: No-Exam Quotes
A no-exam quote can save time, but it doesn’t tell you whether an IUL fits your budget or retirement plan. These three policies are worth discussing with an agent, and each one needs a clear answer on whether it can be issued without a medical exam.
Here’s what’s known about each option, what remains unclear, and what teachers should ask before requesting a quote.
1. Transamerica Financial Foundation IUL
Transamerica Financial Foundation IUL is an indexed universal life policy with flexible premium payments and rider options. It may be worth reviewing if you want permanent life coverage and need to ask about ways to adjust premiums over time.
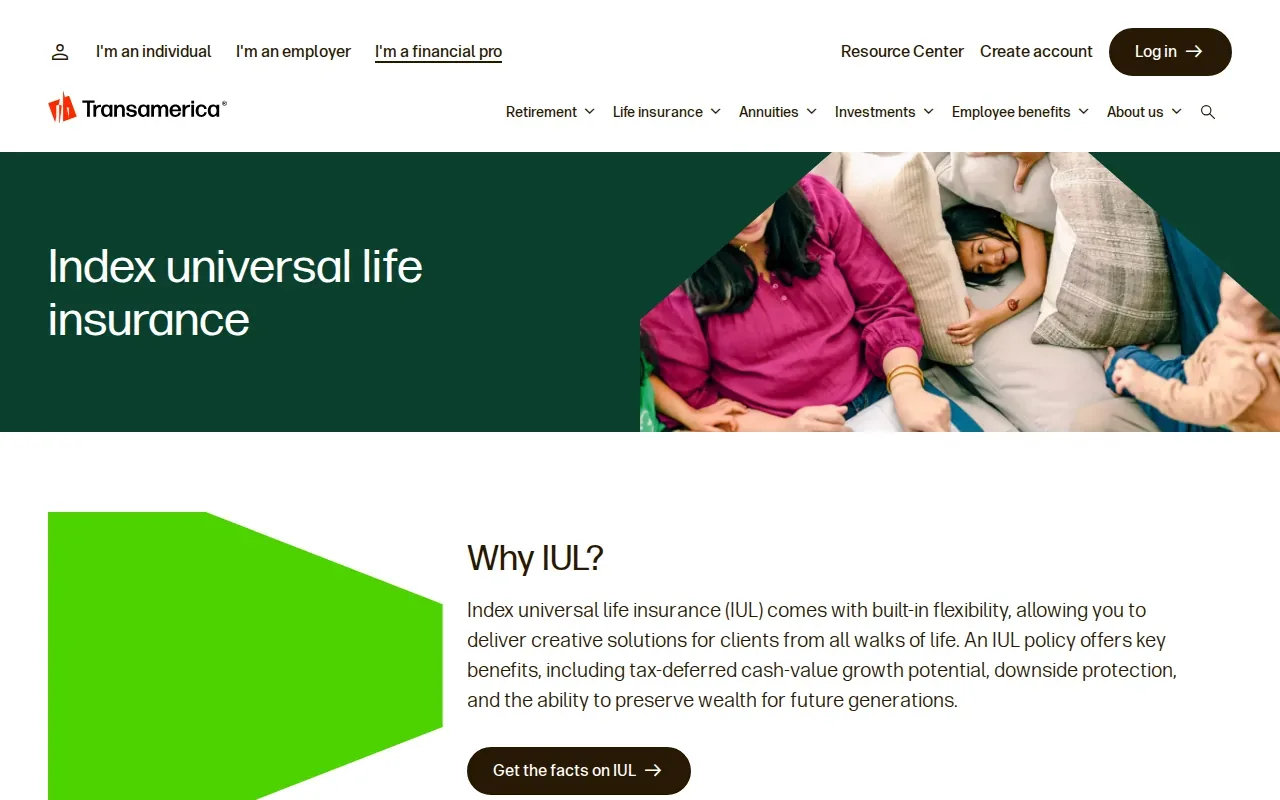
The policy can be customized for different clients. Ask whether a no-medical-exam application is available, what health questions apply, and whether exam-free approval depends on age or coverage amount. Don’t assume “flexible” means you can skip underwriting. Ask the agent to confirm the exact application path for your age, health history, and requested death benefit.
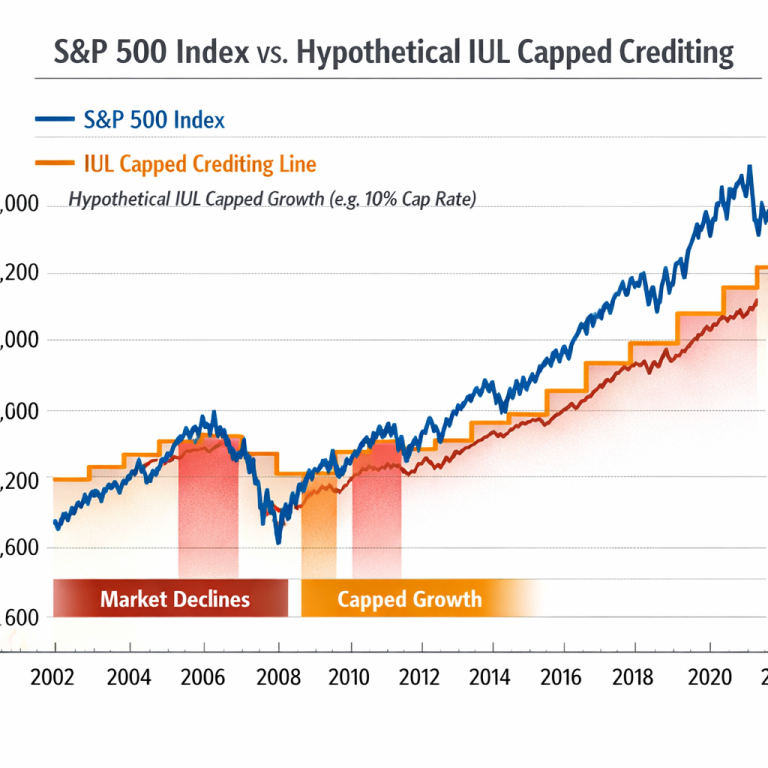
An IUL combines a death benefit with a cash-value account. Part of each premium covers policy costs. Any amount left after charges may go toward cash value. The insurer can credit interest based on an index’s performance, subject to contract terms such as a cap and a floor. The cash value doesn’t own shares in the index.
A floor can limit index-linked interest crediting during a down period, but it doesn’t stop policy charges. That distinction matters. If credited interest is low while insurance and other costs continue, the policy’s cash value may not grow as shown in an illustration. Ask to see a projection with conservative assumptions, not only a favorable scenario.
Every IUL links cash-value interest to an index in its own way. The terms that matter for your quote still depend on the specific policy contract and illustration.
For a teacher, premium flexibility can sound useful during a summer break or a year with fewer extra duties. But a flexible premium policy still has costs. Paying less than planned may slow cash-value growth or put the policy at risk if the value can’t cover ongoing charges. Ask what minimum payment is needed to keep the policy in force under more than one crediting scenario.
Life Care Benefit Services is an independent insurance agency that can help you discuss coverage needs and request a personalized quote. Exam rules and policy costs for this product come from the quote and the contract, so ask for both in writing.
2. Accumulator Ascent by Symetra
Accumulator Ascent by Symetra is a flexible-premium adjustable life policy with index-linked interest options. Teachers considering an IUL without a medical exam can ask about it and confirm whether exam-free approval is possible.
The word “flexible” refers to premium design, not guaranteed low cost or easy approval. The amount you can pay and the coverage a policy can support depend on its terms and underwriting. Ask whether the application includes a medical exam, a health interview, prescription review, or other checks. A no-exam path, if available, may still involve health questions and approval rules.
Index-linked interest is not the same as investing directly in an index. The policy’s crediting method sets how interest is calculated. A cap can limit the credit in a strong index period. A floor may limit negative index crediting, but it doesn’t erase the cost of insurance or other policy fees. Review the current illustration and the contract’s guaranteed values together.
Insurers don’t always present the same details in the same way. Crediting methods, caps, floors and exam criteria differ from one carrier to the next. That is a reason to ask for written policy details, not a reason to assume the terms match another carrier’s product.
For a teacher whose pay changes across the school year, a flexible payment design may be worth discussing. Still, don’t plan around raising and lowering payments without checking the policy’s limits. Ask the agent to show what happens if you pay less during a tight year, then resume a higher payment later. Request the effect on cash value and the policy’s ability to stay active.
Also ask whether the specific quote includes any living-benefit riders. A rider may let an eligible policyholder access part of the death benefit after a defined health event, but triggers and costs vary.
Use the illustration to compare more than a projected cash-value balance. Check the premium schedule, policy charges, assumptions used for interest credits, and what happens if actual credits are lower. If a quote emphasizes potential growth but doesn’t show the cost of keeping coverage in force, ask for a clearer breakdown.
Life Care Benefit Services can help teachers discuss IUL quotes alongside other life-insurance needs. Treat the quote as a starting point, then read the contract terms before making a decision.
3. Principal Indexed Universal Life Flex II
Principal Indexed Universal Life Flex II is an indexed universal life policy built around flexible premiums. Ask the insurer which ages and coverage amounts it accepts and how its terms may fit your needs.
An eligible age range is not proof that every person in it will be approved. Underwriting rules can depend on health, age, requested coverage, and the insurer’s current application process. Ask whether the quote is preliminary or based on a completed review. Also ask what happens if the insurer requests an exam after you begin an application.
Cash-value potential is not a guaranteed result. An IUL’s cash value depends on premium payments, policy charges, credited interest, and how long the policy stays active. A projection can help show possible outcomes, but it isn’t a promise. Ask the agent to explain both the guaranteed values and the non-guaranteed assumptions in plain language.
Teachers weighing this option against a pension or a 403(b) should first list the job each account is meant to do. A pension may provide retirement income under its own plan rules. A 403(b) is an employer-sponsored retirement plan. An IUL is life insurance with a cash-value feature, so it also has a death benefit and insurance costs. It shouldn’t replace a pension or workplace plan without a broader review of your finances.
Ask how the policy would work if you change districts or leave teaching. Your employment change doesn’t, by itself, explain whether an individual life policy continues; the contract and your payments matter. Confirm who owns the policy, who pays the premium, and what you must do to keep coverage active.
For a budget-conscious buyer, compare the required payment with the amount you can keep paying through a job change or a costly year. Ask for a stress test that uses lower interest-credit assumptions and shows whether the planned premium can support the policy. If the design only works when every payment is made on schedule, be clear about that risk before applying.
This shortlist doesn’t establish a best policy for all teachers. It gives you three named products to ask about. Request written answers about exam requirements, charges, riders, and policy guarantees before comparing projected cash values.
Compare the quote details before you apply
A useful comparison starts with the same questions for each policy. A quote that shows a large projected cash value may use different assumptions from another quote, so look at the inputs as well as the result.
| Decision point | What to ask | Why it matters |
|---|---|---|
| Medical exam | Can this application be approved without an exam? What health checks still apply? | A no-exam path may still include health questions or other underwriting. |
| Premiums | What payment is needed to support the coverage? What happens if I pay less? | Flexible premiums don’t remove policy costs or lapse risk. |
| Fees and charges | What insurance, policy, and rider charges apply over time? | Charges affect cash value even when index credits are low. |
| Index crediting | What cap, floor, and other crediting terms apply? Can they change? | These terms shape possible interest credits, but don’t guarantee a result. |
| Living benefits | Are riders available or included, and what health event triggers a benefit? | Access rules and costs depend on the rider and contract. |
| Policy status | What could cause the policy to lapse, and what options exist if funding changes? | A lapse can affect coverage and may have tax consequences. |
For a teacher, compare the proposed premium with income across the full school year. Include months when you may earn less from tutoring or extra work. Then ask the agent to show how the policy performs if you need to reduce payments for a time.
Life Care Benefit Services works with multiple insurance carriers and provides personalized insurance guidance. You can use its overview of life insurance for teachers with living benefits to frame questions about coverage while you’re alive, then request policy-specific terms.
Frequently asked questions
Can teachers get an IUL without a medical exam?
Sometimes an insurer may have an application path that doesn’t require a medical exam, and you should confirm it for each policy you are quoted. A no-exam application can still involve health questions or other review. Ask whether the policy you’re quoted can be issued without an exam and whether that depends on your age, health, or coverage amount.
Does a no-exam IUL quote mean I’m approved?
No, a quote is not the same as approval. An insurer may need an application and underwriting review before it decides whether to issue coverage or what terms to offer. For an indexed universal life quote as a teacher, ask what information is preliminary and whether the insurer may request more health details or an exam later.
Can an IUL work with a teacher pension or 403(b)?
An IUL may be considered alongside a pension or a 403(b), but it has a different purpose and different costs. It combines life coverage with cash value, while workplace retirement plans follow their own rules. Before adding a policy, compare your retirement needs, existing coverage, and ability to keep paying premiums over time.
Can I use IUL cash value tax-free in retirement?
Don’t assume every withdrawal or loan will be tax-free. Tax treatment depends on how the policy is funded and managed, and what happens if coverage ends. Ask a qualified tax professional to review the specific contract and planned access method. A teacher’s quote should show costs and policy assumptions, not promise a tax result.
What should a teacher look for in an IUL quote?
Ask for the exam requirements, premium schedule, policy charges, index-crediting terms, and rider details in writing. Review how the policy may perform under lower crediting assumptions. Also check what happens if you reduce payments or leave your school district. Those details help you judge whether the plan fits your budget and coverage needs.
Conclusion
Start with the policy whose coverage and payment design fit your needs, not with a claim that it guarantees exam-free approval or retirement growth. Ask Life Care Benefit Services for a personalized quote and written answers about underwriting, charges, and policy guarantees before you apply.